MOFI Turns to Capital Market to Expand Affordable Housing Finance
MOFI targets capital-market funding for housing
The Ministry of Finance Incorporated (MOFI) is seeking to mobilise more capital-market funding for affordable housing projects and long-term mortgages as it works to expand housing finance across Nigeria.
MOFI Managing Director and Chief Executive Officer, Dr Armstrong Takang, said the approach would be driven through the MOFI Real Estate Investment Fund (MREIF), a financing platform established to attract institutional capital into the housing sector. The fund forms part of the Federal Government’s One Million Homes Presidential Initiative.
/ You Might Also Like /
MREIF targets institutional capital for housing
According to MOFI, MREIF was designed as a market-driven platform capable of attracting pension funds and other institutional investors into housing finance.
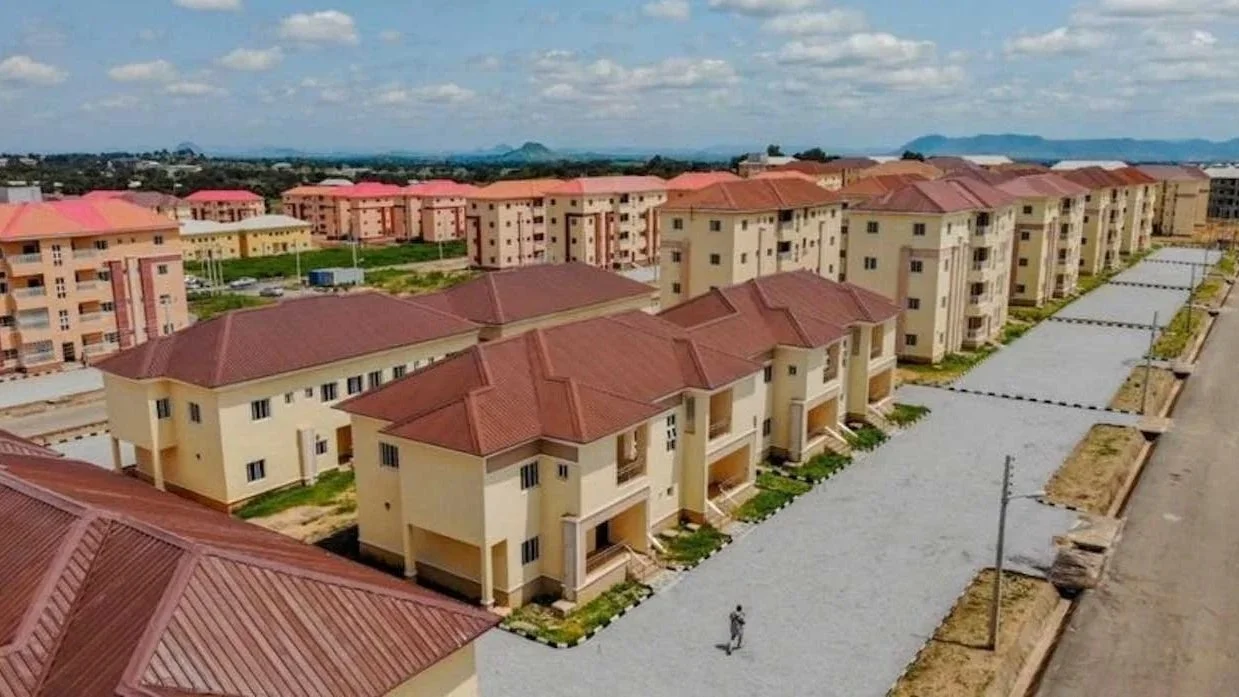
The fund combines public-sector support with private and institutional capital, with the aim of creating a longer-term source of funding for mortgages and residential development. Its commercial tranche was listed on the Nigerian Exchange in November 2025, providing a capital-market structure through which investors can participate in the housing-finance market.
The fund's structure is significant because housing development and mortgage lending require longer-term financing than many conventional funding sources provide. Greater access to institutional capital could therefore help reduce reliance on short-term funding and provide more predictable financing for eligible housing projects and homebuyers.
MREIF expands mortgage financing
MREIF currently provides qualifying borrowers with mortgage financing at a fixed annual interest rate of 9.75 per cent, with repayment periods of up to 20 years and a minimum equity contribution of 10 per cent.
MOFI reported that by June 2026, the fund had provided ₦128 billion in mortgages to 1,859 families across 25 states. The fund had also supported ₦221 billion in property value and contributed to the delivery of 475 housing units through offtake-guarantee projects, according to the Housing TV Africa report.
The figures demonstrate the fund's existing role in expanding access to mortgage finance, while the proposed capital-market approach is intended to provide additional resources to scale the model.
Capital-market funding could support housing supply
The proposed expansion also has implications for housing developers.
MREIF's structure includes support for qualified developers through offtake guarantees. An offtake guarantee provides greater certainty that completed housing units can be purchased or financed, helping developers secure construction funding and reduce some of the risks associated with building homes without confirmed demand.
MOFI also plans to work with the Federal Mortgage Bank of Nigeria, Family Homes Funds Limited and Primary Mortgage Banks to broaden the reach of housing finance. The objective is to strengthen the institutions involved in originating and distributing mortgages to prospective homeowners.
For the housing market, the combination of mortgage finance and developer funding is important because increasing the number of available loans without increasing housing supply could leave affordability constraints unresolved.
Land titles remain a major financing constraint
Housing stakeholders have also identified land administration as an important issue that could determine how effectively additional capital reaches the market.
Former Chairman of the Federal Government's Reform Committee on Land, Dr Ugochukwu Chime, said weak land-titling systems remain a major obstacle to housing finance. He called for reforms that would make property titles easier to obtain, verify and use as security for mortgages and construction loans.
This challenge extends beyond individual homebuyers. Developers also require secure and verifiable land titles to obtain construction finance and attract institutional investment. Faster and more transparent land-registration processes could therefore improve the ability of housing projects to access formal finance.
An ARM Investment Managers report on MREIF similarly identified property-title documentation and registration delays as factors that have slowed mortgage creation.
Stakeholders call for stronger project delivery
While welcoming the capital-market strategy, the Housing Development Advocacy Network (HDAN) urged MOFI to draw lessons from previous federal housing programmes and work with developers with verifiable records of delivering housing projects.
HDAN Executive Director Festus Adebayo also called on credible developers to support the One Million Homes initiative and contribute to increasing affordable housing supply.
Another housing stakeholder, Emmanuel Akinwumi, called for a review of housing and mortgage laws that he said continue to constrain the sector's performance.
These concerns highlight that increasing the amount of money available for housing will not, on its own, guarantee affordable homes. Financing must reach viable projects, secure land, credible developers and households capable of servicing long-term mortgages.
Capital markets could deepen Nigeria's housing finance system
MOFI's strategy represents an effort to connect Nigeria's housing needs with the country's institutional investment market.
MREIF's fund structure was established under a ₦1 trillion programme, with the initial phase combining public and private capital. An ARM Investment Managers report states that the fund seeks to generate long-term returns for investors while supporting mortgage lending and housing supply through eligible financial institutions and developer offtake guarantees.
The listing of the fund's commercial tranche on the Nigerian Exchange also creates a mechanism for institutional investors to participate in housing finance rather than relying solely on direct government expenditure or conventional bank lending.
For investors, developers and policymakers, the effectiveness of the strategy will depend on the quality of projects financed, the security of underlying property assets, mortgage repayment performance and the ability to maintain affordable lending terms.
Outlook for affordable housing finance
MOFI's move towards greater capital-market participation could provide a broader and more sustainable funding base for Nigeria's housing sector. However, the impact will depend on whether additional capital translates into more completed homes and mortgages that households can realistically afford.
Addressing land-title bottlenecks, strengthening mortgage institutions, improving project delivery and maintaining transparency in fund management will remain important as MREIF seeks to scale its role in Nigeria's housing market.
READ MORE