Government Borrowing Puts Pressure on Nigeria’s Private-Sector Credit Market
Rising Government Borrowing Could Squeeze Private-Sector Credit in Nigeria
Nigeria’s increasing reliance on domestic borrowing is intensifying competition for bank credit, raising concerns that attractive government securities yields could limit the availability of affordable financing for businesses, infrastructure projects and households.
/ You Might Also Like /
The issue comes as Nigerian banks emerge from a major recapitalisation exercise that increased their capacity to lend and invest. However, the availability of additional banking capital does not automatically guarantee greater private-sector lending if government securities continue to offer attractive risk-adjusted returns.
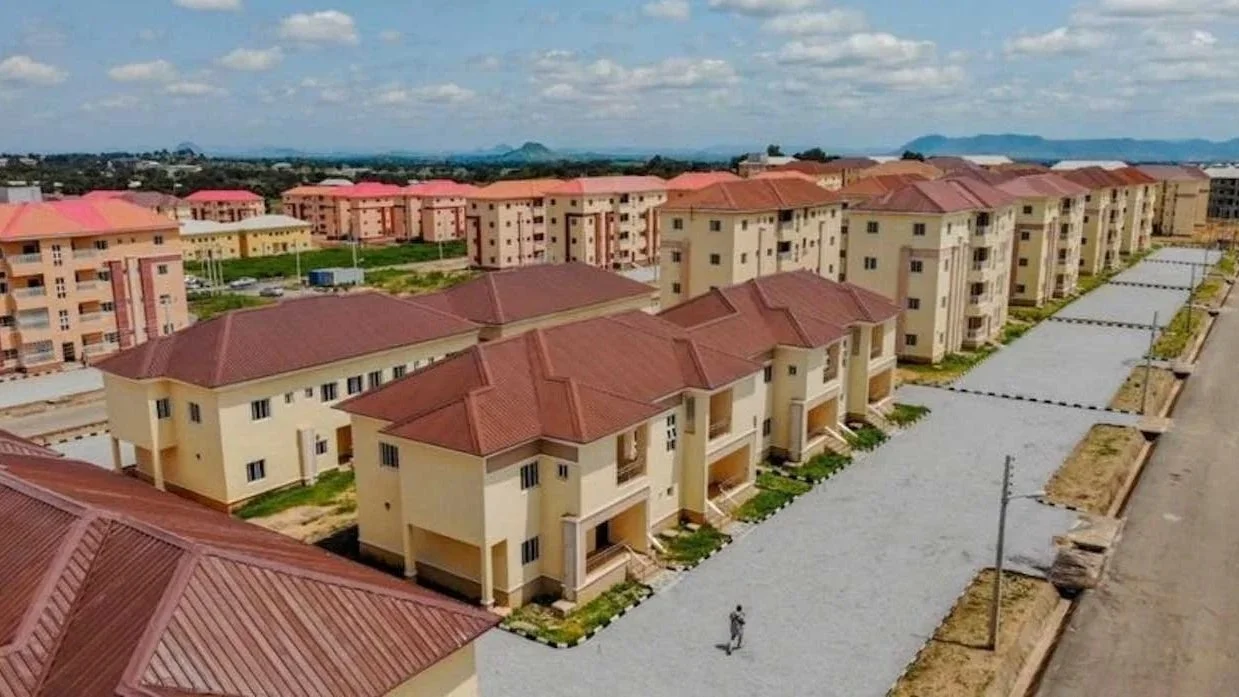
The development is particularly relevant to Nigeria’s property and construction sectors, where developers depend heavily on medium- and long-term financing to acquire land, fund construction, purchase materials and complete projects.
Government Borrowing Increases Competition for Bank Funds
The Federal Government continues to use the domestic capital market to finance fiscal deficits, while Nigerian banks remain significant buyers of government securities.
The International Monetary Fund (IMF), in its 2026 Article IV assessment of Nigeria, identified banks’ holdings of government securities and tight monetary conditions among the factors limiting private-sector credit extension. The IMF reported that Nigerian banks’ holdings of government securities were equivalent to about 22% of total bank assets.
This creates an important allocation question for the banking sector: whether newly raised capital will translate into substantially more lending to businesses or whether a significant portion will continue to flow into government securities.
For banks, the decision involves balancing economic development objectives with credit risk, liquidity requirements and returns for shareholders and depositors.
Private-Sector Credit Has Increased but Remains Below Its Peak
Available data show that private-sector credit has continued to grow, although the increase has been uneven.
Credit to Nigeria’s private sector reached approximately ₦83.43 trillion in July 2026, up from ₦81.04 trillion in May, representing an increase of about ₦2.39 trillion over two months.
However, the July figure remained below the ₦94.61 trillion recorded in February 2026. The IMF also projected a 14.2% increase in private-sector credit in 2026 under its recent economic outlook.
The figures indicate that banks are still extending credit to the private sector, but the central issue is whether lending can expand sufficiently to meet the financing requirements of businesses and investment projects.
Why Government Securities Remain Attractive to Banks
Government securities can offer banks an attractive combination of returns, liquidity and comparatively lower credit risk.
Nairametrics reported that short-term Federal Government debt was offering yields of around 20%, attracting domestic banks alongside pension funds, insurers and international investors.
Commercial lending presents a different risk profile. Banks must assess individual borrowers, monitor loans, manage defaults and potentially recover assets when borrowers fail to meet their obligations.
This makes government securities particularly attractive when their yields provide competitive returns without the same level of credit and operational risk associated with lending to private businesses.
The result is a potential trade-off between government financing requirements and the availability of credit for productive private-sector investment.
IMF Raises the Risk of a Crowding-Out Effect
The IMF has previously identified a relationship between higher bank holdings of sovereign debt and weaker growth in private-sector credit.
This raises the possibility of a crowding-out effect, where increased government borrowing absorbs a larger share of available financial resources and leaves private borrowers competing for the remainder.
Professor Joseph Uwaleke, founding director of the Institute of Capital Market Studies, argued that bank recapitalisation should enable lenders to direct more funding towards economically productive assets, including manufacturing and local production.
Financial economist Dr Godwin Imoibe of the University of Nigeria similarly warned that government securities could draw funds away from entrepreneurs and other private investors.
The views point to the central challenge facing the credit market: government needs financing to meet its expenditure obligations, while businesses require affordable capital to expand production and investment.
Property Developers Face Higher Financing Pressure
The implications are significant for Nigeria’s property market because real estate development requires substantial upfront capital and projects often take months or years to generate returns.
Developers typically need financing for land acquisition, site preparation, building materials, labour, infrastructure and other construction costs. Higher borrowing costs can therefore increase the total cost of delivering a housing or commercial project.
The Nairametrics analysis notes that higher financing costs could make property and infrastructure projects commercially unviable.
For developers, this can result in several outcomes: projects may be delayed, development phases may be reduced, or developers may rely more heavily on equity and internally generated funds.
Smaller developers could face greater pressure because they generally have fewer financing alternatives and may have less capacity to absorb prolonged increases in borrowing costs.
Housing Affordability Could Also Be Affected
The financing challenge extends beyond developers to potential homebuyers.
Where developers face higher financing costs, some of those costs can eventually be reflected in property prices. Buyers who require mortgages may also face higher borrowing costs, reducing the amount they can afford to borrow.
This can widen the gap between household purchasing power and the cost of newly developed housing.
The effect is particularly important in a market where housing supply already requires significant private capital. If financing becomes more expensive or less accessible, developers may concentrate on projects with higher expected returns rather than lower-cost housing.
That could constrain the supply of homes targeted at middle- and lower-income households.
Infrastructure Projects Also Depend on Credit Availability
The competition for credit extends beyond residential property.
Infrastructure businesses, manufacturers and other capital-intensive companies require long-term financing to purchase equipment, expand capacity and develop facilities.
According to the analysis, manufacturers may postpone investment, operate below capacity or rely more heavily on internally generated funds when affordable long-term credit becomes difficult to secure.
For infrastructure and property developers, this can affect project timelines and investment decisions, particularly where projects require significant debt financing.
The consequences can extend into the wider economy because delayed infrastructure and commercial investment can slow the development of new business locations and urban growth corridors.
Bank Recapitalisation Creates a New Test
Nigeria’s recent bank recapitalisation programme has increased attention on how the additional capital will be deployed.
The purpose of recapitalisation extends beyond strengthening banks' balance sheets. A stronger banking sector should also have greater capacity to support economic activity through credit and investment.
However, banks still have to allocate capital according to risk and return considerations.
The current environment therefore presents a test of whether increased bank capital will translate into significantly greater financing for productive sectors or whether government securities will continue to absorb a substantial portion of banks' investment capacity.
Government Has Competing Financing Needs
The Federal Government faces substantial expenditure obligations and continues to rely on borrowing to finance budget deficits.
At the same time, debt-service obligations place pressure on government revenue, increasing the incentive to access domestic capital markets, particularly when foreign financing is more expensive or constrained.
Domestic borrowing provides government with an important source of financing, but sustained dependence on the local market can have broader implications for the allocation of financial resources.
The challenge is therefore not simply the volume of government borrowing. It is also how borrowing interacts with interest rates, bank balance sheets and the availability of long-term financing for private investment.
What It Means for Nigeria’s Property Investment Market
For the property sector, the credit-market environment could influence both development activity and investment strategies.
Developers with strong balance sheets may be better positioned to continue projects using equity or alternative financing structures, while smaller firms could face greater difficulty securing affordable bank loans.
Investors may also pay greater attention to projects with stronger cash-flow visibility and shorter development cycles if financing costs remain elevated.
For housing, the most important consideration is whether the financing environment supports the construction of new units at price points that households can afford.
If credit remains expensive, developers may have fewer incentives to pursue lower-margin affordable housing projects, while buyers may struggle to obtain mortgages large enough to purchase newly built homes.
Outlook
Nigeria’s domestic borrowing strategy will continue to have implications for the distribution of credit across the economy.
Private-sector credit has increased, and the IMF expects further growth in 2026, but banks’ substantial exposure to government securities means competition for financial resources remains an important consideration.
For the property and infrastructure sectors, the key issue is whether Nigeria’s banking system can expand long-term lending alongside government financing requirements.
The outcome will influence the cost of development capital, the pace at which businesses expand and the ability of developers to deliver housing and infrastructure at commercially viable prices. As banks deploy the capital raised through recapitalisation, the balance between sovereign lending and productive private-sector credit will remain an important factor for Nigeria’s investment and property markets.
READ MORE