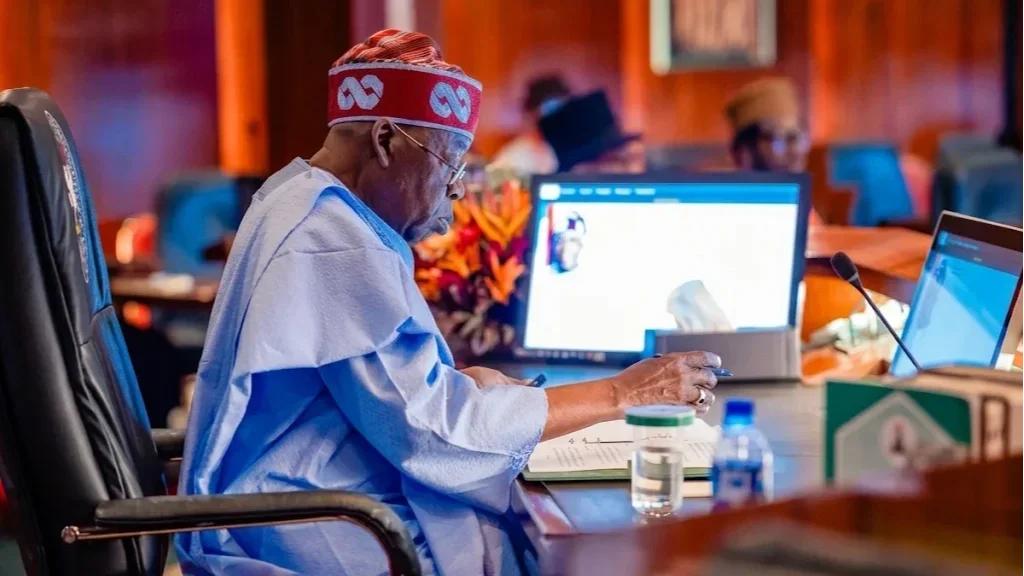
President Bola Tinubu says more than 2,300 Nigerians across 27 states have accessed mortgages through the ₦1 trillion MOFI Real Estate Investment Fund
President Bola Tinubu has highlighted the Federal Government's housing finance initiatives, saying more than 2,300 Nigerians across 27 states have accessed ₦160 billion in mortgages through the MOFI Real Estate Investment Fund (MREIF). The President also outlined expanded mortgage facilities through the Federal Mortgage Bank of Nigeria (FMBN), pension-backed equity contributions and social housing programmes as part of efforts to improve access to homeownership.
/ You Might Also Like /

In a statement outlining his administration's housing interventions, Tinubu said the government established the ₦1 trillion MREIF to increase access to long-term housing finance and help working Nigerians move from renting to homeownership.
Under the programme, eligible applicants can access mortgages of up to ₦100 million at a fixed annual interest rate of 9.75 per cent, with repayment periods of up to 20 years and an initial equity contribution of 10 per cent.
The President said the fund had supported more than 2,300 mortgages worth ₦160 billion across 27 states. The latest figures represent an increase from the ₦140 billion in mortgages and 2,018 beneficiaries reported by the State House in August 2026.
MREIF expands access to long-term mortgage finance
MREIF, sponsored by the Ministry of Finance Incorporated (MOFI), provides long-term funding through participating financial institutions to support eligible homebuyers and housing developers.
Its ₦1 trillion programme size is designed to mobilise capital for mortgage lending and support housing delivery. ARM Investment Managers manages the fund, while participating banks and mortgage institutions originate loans for qualified applicants.
The 9.75 per cent mortgage rate offers a longer-term financing option than many conventional commercial lending facilities. However, applicants must still satisfy income, credit, property valuation and documentation requirements before securing approval.
The programme's stated terms allow eligible borrowers to access up to ₦100 million over a maximum of 20 years. MREIF's published eligibility information also identifies Nigerian citizenship, satisfactory income and credit assessment, and supporting documentation as key requirements.
Tinubu illustrated the arrangement with a ₦10 million property. Under his example, a buyer would provide ₦1 million as an initial contribution and repay approximately ₦85,400 monthly over 20 years.
The illustration is broadly consistent with a ₦9 million loan amortised over 240 months at 9.75 per cent annually. Actual repayment obligations may differ depending on the lender's terms, fees, insurance and other charges.
FMBN offers mortgages of up to ₦50 million at 6 per cent
The President also pointed to the Federal Mortgage Bank of Nigeria's National Housing Fund (NHF) mortgage facility, which allows eligible contributors to access loans of up to ₦50 million at an annual interest rate of 6 per cent.
The facility offers repayment periods of up to 30 years and supports the purchase, construction, improvement or renovation of owner-occupied homes. FMBN provides the funding through accredited primary mortgage banks, which lend to eligible NHF contributors.
The longer repayment period and lower interest rate could make the facility more accessible to some households than shorter-term commercial loans. However, access depends on an applicant's NHF contribution history, income, repayment capacity, property value and the bank's assessment.
The two federal mortgage programmes serve complementary roles. MREIF provides mortgage funding through participating financial institutions, while FMBN's NHF facility serves registered contributors under the National Housing Fund framework.
Pension savings can support mortgage deposits
Tinubu also highlighted the option for eligible pension contributors to use part of their Retirement Savings Account (RSA) balance to fund the initial equity contribution required for a residential mortgage.
Under guidelines issued by the National Pension Commission (PenCom), eligible active contributors may access up to 25 per cent of their RSA balance for this purpose. The provision aims to address one of the barriers to homeownership: raising the upfront deposit required by mortgage lenders.
The facility does not allow every pension contributor to withdraw funds automatically. Applicants must satisfy PenCom's conditions, including having made contributions for at least 60 months and meeting the requirements for an eligible residential mortgage. Contributors who are close to retirement also face restrictions.
The President further encouraged eligible married couples to apply jointly where the relevant mortgage programme permits it. Combining income and meeting the lender's affordability requirements could improve a couple's borrowing capacity, although joint applications do not guarantee approval.
Government expands social housing for vulnerable households
Beyond mortgage financing, Tinubu said the government was using social housing programmes to support Nigerians who cannot afford conventional home loans.
He cited the role of Family Homes Funds Limited (FHFL) in delivering housing for vulnerable and underserved households. He also referred to completed homes for widows in Kaduna and the wives of fallen military personnel in Ibadan.
The FHFL's published programme information confirms the delivery of 100 homes for widows in Kaduna and 50 homes for families of fallen military personnel in Ibadan. Its website also reports more than 200 social homes delivered for vulnerable and underserved households, a broader figure than the specific programme total highlighted in the President's statement.
The government has also set a target of 77,400 homes under the Renewed Hope Social Housing Programme. The plan envisages 100 homes in each of Nigeria's 774 local government areas, with a focus on low-income and vulnerable households.
The 77,400 figure represents a programme target, not completed housing delivery. The government will need to provide details on funding, land availability, construction progress, beneficiary selection and delivery timelines to demonstrate how the target will be achieved.
More than 15,000 homes reportedly under construction
Tinubu said more than 15,000 homes were under construction nationwide through the Renewed Hope Cities and Estates Programme.
The initiative forms part of the Federal Government's broader effort to increase housing supply through large-scale developments and partnerships with public and private-sector institutions.
The figure points to a substantial construction pipeline, but homes under construction should not be treated as completed or available for occupation. Their contribution to housing supply will depend on project completion, infrastructure provision, pricing and access to financing.
The President also cited 100 free homes delivered to widows in Kaduna and 50 homes for wives of fallen military personnel in Ibadan as examples of the government's social housing interventions.
Housing finance reforms face affordability and supply challenges
The programmes outlined by the President address different parts of Nigeria's housing challenge. MREIF and FMBN focus on mortgage access, pension-backed contributions help eligible workers raise deposits, while FHFL and the social housing programme target households that cannot afford conventional mortgage financing.
However, expanding mortgage access alone will not resolve the country's housing shortage. Borrowers need completed homes at prices that match their incomes, while developers require access to land, infrastructure, construction finance and reliable approval processes.
The scale of mortgage lending also needs to be considered against the size of the housing market. Although MREIF has expanded its reach across 27 states, the number of beneficiaries remains limited relative to the number of Nigerian households seeking affordable housing.
The ₦100 million MREIF ceiling and ₦50 million FMBN limit are maximum loan amounts, not guaranteed entitlements. A household's actual borrowing capacity will depend on income, credit assessment, the property's value and the lender's requirements.
The Federal Government's next challenge is therefore to translate its financing commitments and construction pipeline into completed, affordable homes that eligible households can access. Progress will depend not only on the amount of mortgage funding mobilised, but also on the cost of housing, the pace of construction and the transparency of beneficiary selection.
READ MORE