Royal Exchange Prudential Life Begins Asset Sale After Licence Revocation
REPRU begins asset realisation
Royal Exchange Prudential Life Plc (REPRU) has moved into the asset-realisation phase of its winding-up process, with the insurer’s receiver and provisional liquidator putting various company assets up for auction.
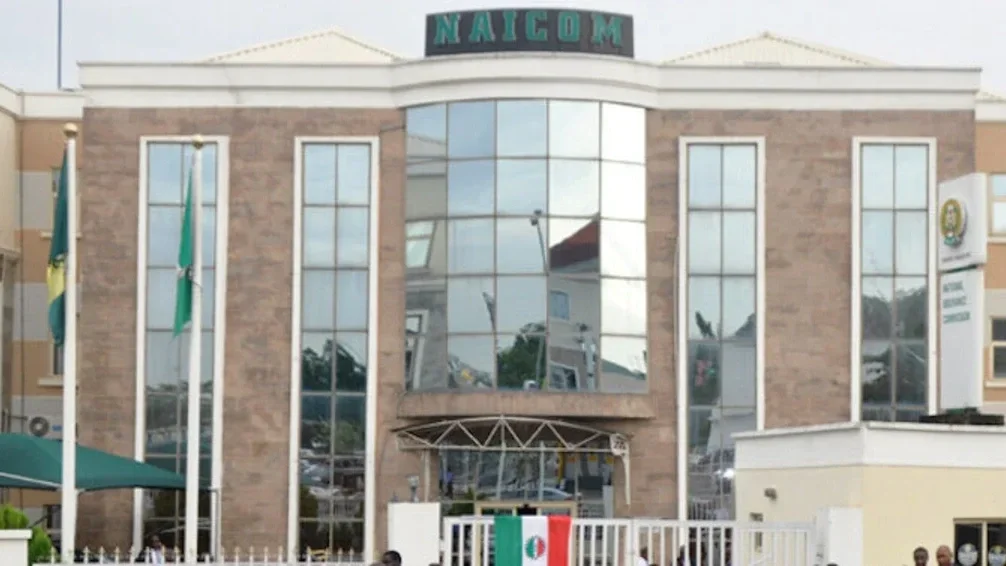
The development follows the National Insurance Commission’s (NAICOM) revocation of REPRU’s operating licence after the insurer failed to meet the statutory minimum capital requirement under the Nigerian Insurance Industry Reform Act (NIRA) 2025.
/ You Might Also Like /
Interested buyers have until October 9, 2026, to participate in the auction, according to the notice issued by the receiver and provisional liquidator.
Asset Realisation Begins After Licence Revocation
The auction represents a significant step in the winding-up of REPRU, moving the company from regulatory intervention into the process of converting its assets into funds.
NAICOM appointed Titilayo Akinlawon, SAN, as receiver and provisional liquidator after cancelling the insurer’s certificate of registration. The appointee is responsible for taking control of the company’s affairs, realising its assets and addressing its outstanding liabilities within the applicable liquidation framework.
The proceeds from the asset sales are expected to form part of the resources available for settling obligations to creditors, policyholders and other stakeholders.
Capital Shortfall Triggered Regulatory Action
NAICOM revoked REPRU’s certificate of registration with effect from August 3, 2026, after the company failed to meet the new minimum capital requirements introduced under the insurance-sector recapitalisation exercise.
The regulator had set July 31, 2026 as the compliance deadline for insurers and reinsurers to meet the revised capital thresholds.
REPRU was among the operators that failed to satisfy the requirements, resulting in licence cancellation and an order for the winding-up of its operations.
The case demonstrates the consequences facing insurance companies that fail to meet the capital requirements established under the industry's latest reform programme.
Recapitalisation Reshapes Nigeria’s Insurance Market
NAICOM’s recapitalisation programme was designed to strengthen insurers’ balance sheets, improve their capacity to absorb risks and enhance the sector’s ability to meet policyholder obligations.
According to earlier industry reporting, 48 insurance companies and two reinsurance firms met the new requirements and were relicensed, while operators that failed to comply faced regulatory action.
The intervention against REPRU therefore forms part of a wider restructuring of Nigeria’s insurance industry rather than an isolated corporate event.
For investors and policyholders, the outcome also highlights the importance of insurers maintaining sufficient capital to support their obligations and remain operational under changing regulatory requirements.
Royal Exchange Plc Is No Longer REPRU’s Owner
Despite the Royal Exchange name, the insurer undergoing liquidation is separate from Royal Exchange Plc.
Royal Exchange Plc disposed of its interest in REPRU in August 2022 and has subsequently clarified that the life insurer is no longer its subsidiary or affiliate.
The listed company said REPRU’s financial position, operations, assets, liabilities and regulatory obligations are separate from its own and that NAICOM’s action against REPRU does not affect Royal Exchange Plc’s financial or regulatory position.
This distinction is important for investors because the licence revocation and asset-realisation process relate specifically to REPRU.
Policyholders and Creditors Now Await Asset Realisation
The auction places greater focus on how REPRU’s remaining assets will be converted into funds and ultimately applied towards its outstanding obligations.
Policyholders, creditors and other stakeholders will have a particular interest in the process because asset realisation is central to the orderly winding-up of the insurer.
The receiver's role is therefore not limited to selling assets but also involves managing the company's affairs and progressing the settlement of liabilities within the regulatory framework.
Regulatory Enforcement Could Strengthen Market Discipline
The REPRU case underscores the shift towards stronger capital requirements and regulatory enforcement across Nigeria’s financial-services industry.
For the insurance sector, stronger capitalisation should provide companies with greater capacity to absorb claims, invest in operations and withstand financial shocks. However, operators unable to raise the required capital face increasingly limited options, including restructuring, acquisition or loss of their operating licences.
The result could be a smaller but better-capitalised insurance market, with regulators placing greater emphasis on solvency and long-term financial sustainability.
Implications for Investors and the Wider Property Market
Although REPRU’s licence revocation is primarily an insurance-sector development, its implications extend to investment and real estate.
Insurance companies are important institutional investors in Nigeria and can provide long-term capital for infrastructure, property and other real assets. A stronger insurance industry can therefore contribute to deeper pools of institutional capital for long-term investments.
Conversely, the failure of an insurer and subsequent liquidation can raise concerns about the protection of policyholders and the reliability of institutional capital providers.
For the property market, a more resilient insurance sector could support greater participation in property-related investments and provide stronger risk-management capacity for developers, investors and homeowners.
Outlook
REPRU’s asset auction marks the latest stage in Nigeria’s insurance-sector recapitalisation drive and demonstrates that the new capital requirements carry significant regulatory consequences.
With the October 9 auction deadline approaching, attention will now shift towards the value realised from the assets, the treatment of outstanding liabilities and the protection of affected stakeholders.
More broadly, the case illustrates the balance regulators must maintain between enforcing stronger capital standards and ensuring an orderly transition for policyholders, creditors, investors and the wider financial market.
READ MORE