Nigerian insurance stocks are struggling to attract investor confidence despite significant profit growth across some of the country’s largest listed insurers, as concerns over share dilution, earnings quality and cash flow continue to weigh on market valuations.
/ You Might Also Like /

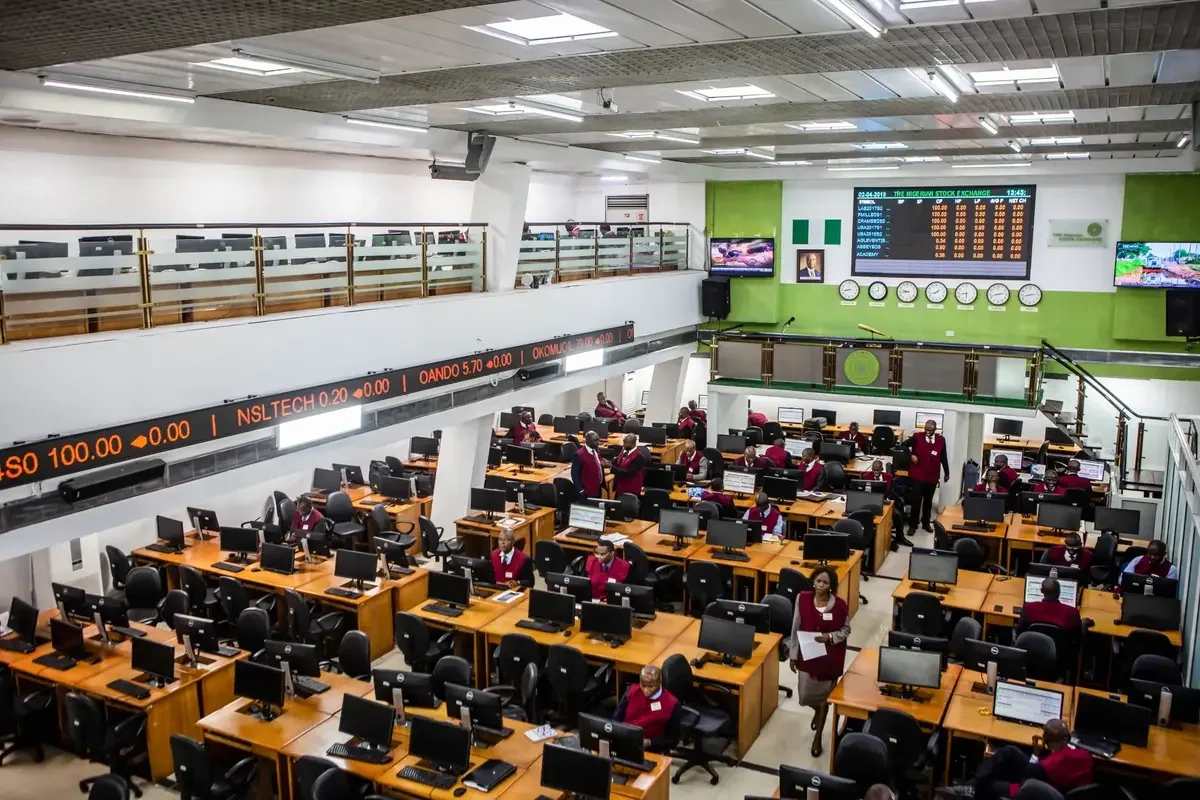
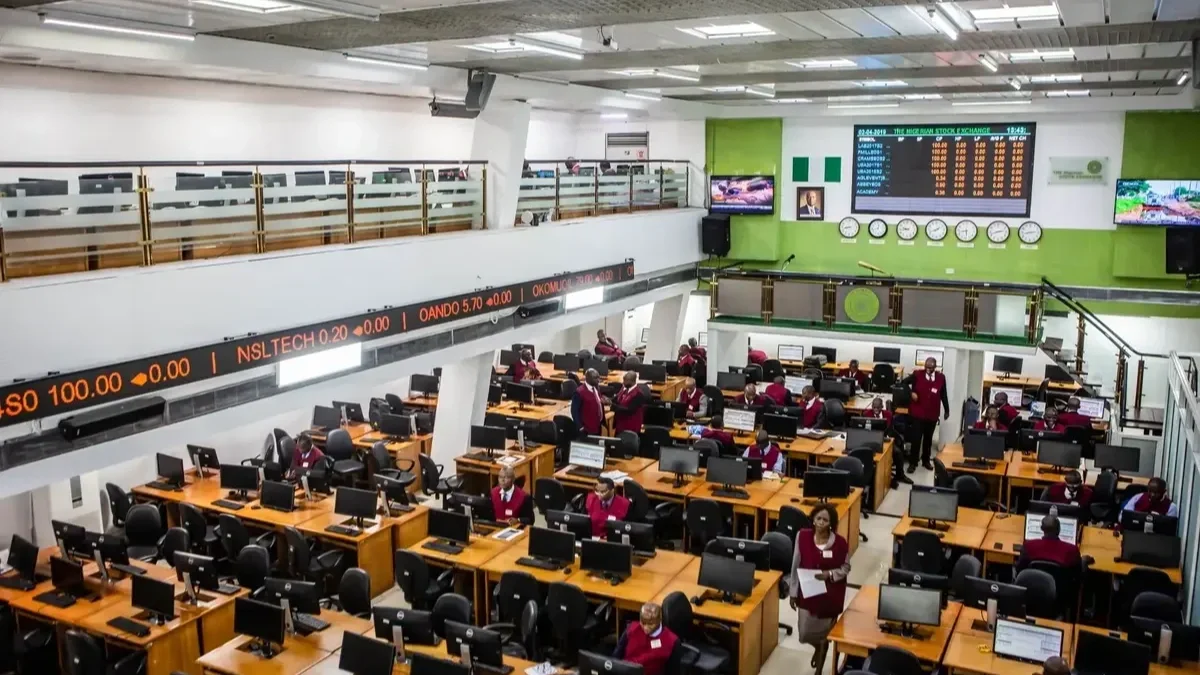
The sector’s weak performance stands in contrast to the broader Nigerian equities market, which has recorded substantial gains in 2026. The Nigerian Exchange (NGX) Insurance Index declined by 5.52% in October and was down 13.64% year-to-date as of early November, making it the only major sector index in negative territory.
By comparison, the banking index had gained 60%, the oil and gas index 128%, while the NGX All-Share Index had risen by 60%.
The divergence highlights investors’ reluctance to reward insurance companies for improved reported earnings, particularly as the industry adjusts to higher regulatory capital requirements and faces questions about the sustainability of its profits.
Strong earnings fail to lift insurance share prices
Several major insurance companies reported significant profit increases in their nine-month results, but their share prices have largely failed to reflect the improved performance.
AIICO Insurance Plc recorded a 27% increase in nine-month profit before tax to ₦19.4 billion, while its profit after tax reached ₦17.3 billion, exceeding its earlier forecast of ₦14.4 billion. Despite the earnings performance, its shares fell 6.6% on the day highlighted in the report.
AXA Mansard Insurance Plc recorded an 81% increase in profit after tax to ₦10.9 billion, more than double its forecast of ₦5.1 billion. Coronation Insurance Plc reported a 71% increase in profit, while NEM Insurance Plc generated ₦26.8 billion in nine months, exceeding its full-year profit for 2025.
However, the share-price performance of several insurers remained weak.
AXA Mansard traded at approximately ₦11.65 in early November, down from ₦13.70 at the start of the year. Coronation Insurance declined from ₦3.25 to about ₦2.22, while Cornerstone Insurance and AIICO Insurance recorded year-to-date declines of approximately 24% and 6%, respectively.
Custodian Investment Plc stood out, gaining about 50% during the year, although its shares had retreated from their April high of approximately ₦87.
Capital requirements raise concerns over shareholder dilution
One major factor weighing on investor sentiment is the industry's recent recapitalisation exercise.
Under the Nigerian Insurance Industry Reform Act 2025, insurance companies had until July 2026 to meet new minimum capital requirements. Several operators raised additional funds through equity issuance, strengthening their balance sheets but increasing the number of shares in circulation.
The National Insurance Commission reported that 43 insurance companies and reinsurers had complied with the new capital requirements.
Although stronger capital positions could improve insurers’ capacity to underwrite larger risks, additional share issuance can dilute existing shareholders' ownership and reduce earnings attributable to each share if profit growth does not keep pace.
Coronation Insurance's share count increased by almost a fifth following its ₦9.2 billion capital raise. AXA Mansard shareholders also approved a rights issue of up to ₦18.3 billion, adding to investor considerations about potential dilution.
The market's response suggests that investors want evidence that the additional capital will translate into stronger earnings per share, improved returns on equity and more consistent shareholder distributions.
Investment income drives profits as underwriting faces pressure
The source of earnings growth also appears to influence how investors value insurance companies.
A significant portion of the sector's recent profit growth came from investment portfolios rather than core insurance underwriting activities. High yields on Nigerian government bonds and Treasury bills allowed insurers with substantial fixed-income investments to generate stronger returns.
However, investment income may become less supportive if interest rates and fixed-income yields decline.
AIICO's results illustrate this distinction. Investment income contributed more to its profit growth than its insurance operations, while its underwriting margin fell to approximately 8%.
Some insurers also faced higher reinsurance costs and foreign-exchange losses, adding pressure to their underlying insurance operations.
For investors, sustainable underwriting performance remains important because it reflects insurers' ability to price risks appropriately, manage claims and generate profits from their core business rather than relying heavily on investment market conditions.
Cash flow concerns add to investor caution
The conversion of reported profits into actual cash presents another challenge for the sector.
NEM Insurance recorded an operating cash outflow of ₦1.1 billion in the nine months, compared with an inflow of ₦10.3 billion in the corresponding period. The company's outstanding premiums receivable also increased from less than ₦100 million to ₦9.5 billion.
This raises questions about how quickly insurers collect premiums and convert reported earnings into cash available to meet claims, operating expenses and other financial obligations.
Custodian Investment also reported negative operating cash flow, although the inclusion of its merchant banking operations complicates direct comparisons.
The distinction between accounting profits and cash generation remains important in assessing insurers' financial strength, particularly as they expand their capital bases and seek to improve underwriting capacity.
Valuations remain low despite earnings growth
The disconnect between reported earnings and share-price performance has left several listed insurers trading at relatively low earnings multiples.
Based on annualised nine-month earnings, AIICO Insurance trades at approximately 5.6 times earnings, Custodian Investment at 5.9 times, AXA Mansard at 7.2 times and NEM Insurance at 7.9 times.
These valuations indicate that investors are assigning relatively modest multiples to the sector despite the reported profit increases.
However, low valuations do not automatically indicate that insurance stocks are undervalued. Investors must also consider earnings sustainability, capital requirements, cash generation, underwriting performance and the ability of companies to deliver consistent returns.
Dividends and full-year results could influence sentiment
Dividend payments and the forthcoming full-year financial results could provide important signals about whether the sector's improved profitability will translate into stronger shareholder returns.
Cornerstone Insurance's last dividend payment of 28 kobo represents a yield of approximately 6% at the share price considered in the report, while Custodian offers a yield of about 4%.
Coronation Insurance has indicated that it hopes to resume dividend payments within a year, while AXA Mansard did not pay a dividend in 2026.
The next set of full-year results, expected early in 2027, will provide further evidence of whether insurers can sustain earnings growth following the recapitalisation exercise.
For now, the sector faces the challenge of converting stronger capital positions and higher reported profits into consistent underwriting performance, reliable cash generation and improved shareholder returns.
READ MORE