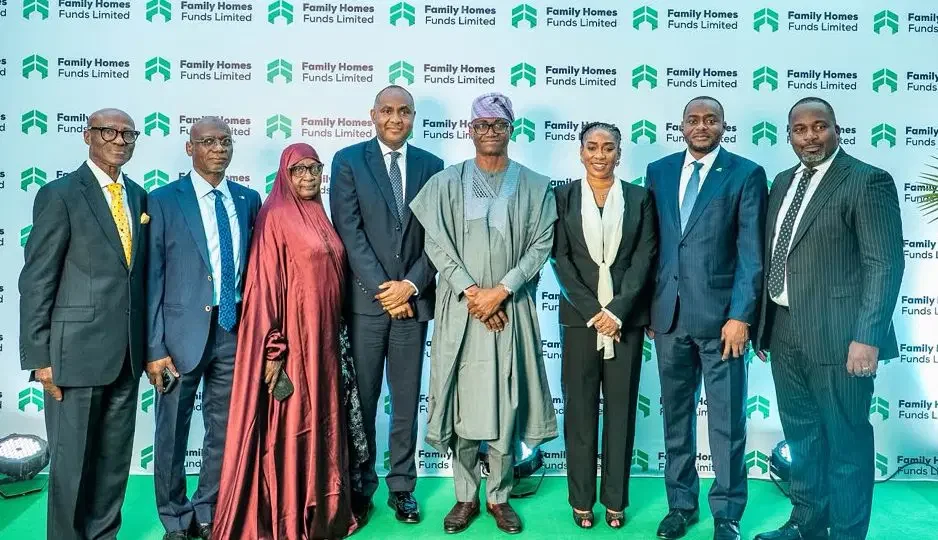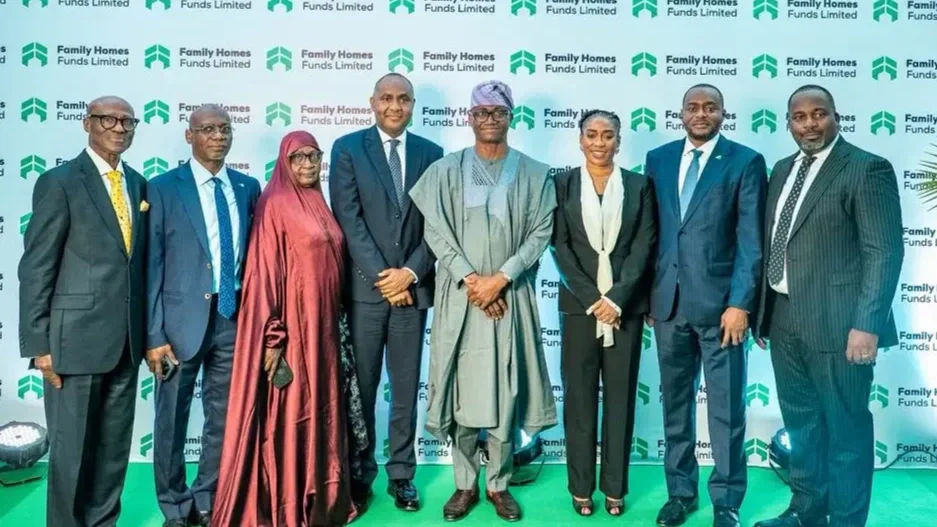
Family Homes Funds Limited has unveiled a new corporate identity as it seeks to expand housing finance
Family Homes Funds Limited (FHFL) has unveiled a new corporate identity as the housing finance institution seeks to expand its operations and address Nigeria’s estimated 15 million-unit housing deficit through increased investment, mortgage partnerships and infrastructure financing.
/ You Might Also Like /

The institution said it had financed more than 15,900 homes since commencing operations in 2018, with over 18,000 additional homes in its development pipeline. It also reported a presence across 70 project sites in 19 states and the Federal Capital Territory.
The rebranding accompanies a broader effort to diversify funding beyond government sources, attract private capital and strengthen partnerships with state governments, developers and financial institutions.
For Nigeria’s housing market, the more important test will be whether the institution can convert its financing capacity and project pipeline into completed homes that households can afford.
FHFL Expands Beyond Government Funding
FHFL Managing Director and Chief Executive Officer Abdul Mutallab Mukhtar said the institution had expanded its funding model to attract private capital and financing from other sources, including development finance institutions.
Its loan portfolio has exceeded ₦100 billion, according to the institution, which attributed the performance of its facilities to its lending standards and due diligence.
The organisation operates several financing programmes covering affordable housing construction, homeownership, rental housing, land and infrastructure development, and social housing.
These programmes target different constraints across the housing value chain. Developer financing supports the construction of homes, while mortgage partnerships aim to help eligible buyers purchase completed properties. Infrastructure financing addresses the roads, drainage, electricity and water supply that developers need to prepare land for housing.
The approach reflects the fact that Nigeria’s housing shortage cannot be addressed through construction finance alone. Developers also need serviced land, while prospective homeowners require financing that matches their incomes and repayment capacity.
More Than 18,000 Homes in Development Pipeline
FHFL reported that more than 18,000 homes were in its development pipeline as it seeks to scale delivery through partnerships with public and private-sector organisations.
However, a pipeline represents planned or developing projects rather than homes already completed and occupied. The pace at which these units reach the market will depend on project readiness, financing, construction costs, infrastructure provision and effective coordination among partners.
The institution has also expanded its involvement in student accommodation and rental housing. Its management said it had financed student accommodation projects at 12 locations, with construction ongoing at 10 sites. Two completed projects in Akwa Ibom and Delta states were expected to be commissioned in the coming weeks.
These investments could broaden the supply of organised rental accommodation for students and young professionals, although their ultimate impact will depend on the number of bed spaces delivered, rental prices and access for intended beneficiaries.
FHFL has also supported social housing initiatives for vulnerable households. Its reported projects include 100 homes for women, including widows, in Kaduna State, alongside other interventions for vulnerable groups and families of fallen military personnel.
Mortgage Financing Targets Lower Borrowing Costs
FHFL is also seeking to improve access to homeownership through partnerships with primary mortgage institutions.
Under its homeownership financing model, the institution combines funding arrangements with mortgage lenders to help eligible buyers acquire homes. Mukhtar said the structure could reduce mortgage pricing to about 15 per cent or lower, depending on the applicable terms and repayment arrangements.
Lower financing costs could improve affordability by reducing the cost of borrowing over the life of a mortgage. However, a rate of around 15 per cent may still present a substantial barrier for lower-income households, particularly when combined with deposits, legal fees, service charges and other homeownership expenses.
The impact will therefore depend on eligibility requirements, the availability of suitable homes, loan tenures and whether the target households can sustain repayments.
FHFL’s model also means that prospective buyers generally access financing through partner mortgage institutions rather than borrowing directly from the fund. The efficiency of these partnerships will be important in determining how quickly eligible households can move from application to homeownership.
Land and Infrastructure Remain Critical to Affordable Housing
The institution has identified partnerships with state governments as important to reducing housing development costs. Access to land and the provision of essential infrastructure can significantly influence the final price of a home.
Where developers must independently finance roads, drainage, electricity and water supply, those costs can raise the amount they need to recover from buyers. Public-private partnerships that prepare land and provide infrastructure could help reduce some of these expenses.
FHFL’s Land and Infrastructure Development Fund is designed to support this part of the housing value chain. The institution is also exploring climate-resilient construction methods and energy-efficient technologies to improve building performance and reduce long-term costs.
For housing investors and developers, these interventions could create opportunities to deliver projects in locations where infrastructure gaps have constrained development. Yet the results will depend on the availability of serviced land, transparent project selection, construction efficiency and whether savings translate into lower prices for homebuyers.
Delivery Will Matter More Than Rebranding
Nigeria’s estimated 15 million-unit housing deficit underscores the scale of the challenge facing housing institutions, developers and policymakers. FHFL’s expanded funding model and reported project pipeline offer a potential route to increasing supply, but their significance must ultimately be measured through delivery.
The key indicators will include the number of homes completed and occupied, the affordability of those homes, the volume of mortgages reaching eligible households and the institution’s ability to mobilise sustainable funding.
The distinction between financing homes and delivering homes is particularly important. A growing pipeline can indicate future activity, but it does not automatically resolve the shortage of housing that households can afford today.
FHFL’s new identity marks a change in how the institution presents its role in the market. Its long-term contribution, however, will depend on whether its financing programmes produce more completed homes, expand access to mortgages and reduce the costs that prevent many Nigerians from securing adequate housing.
READ MORE