Brokers, Flippers and Short-Lets Draw Scrutiny as Nigeria’s House Prices Rise
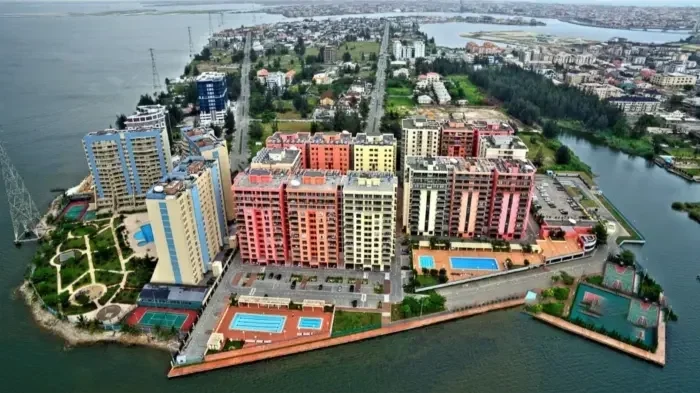
Brokers and speculators face scrutiny as property prices rise
Nigeria’s real estate market is facing growing scrutiny over the role of property brokers, flippers and short-let operators in driving up property prices, as rising housing costs continue to weaken affordability across major urban centres.
/ You Might Also Like /
While some industry professionals acknowledge that brokers and speculative investors can amplify price increases, others argue that the fundamental drivers remain the rising cost of land, cement, steel, labour, diesel, imported materials, financing, infrastructure and statutory charges.
The debate highlights a more complex property market in which underlying costs are interacting with investment strategies, market expectations and limited housing supply.
A New Brokerage Model Emerges
For decades, traditional estate agents primarily earned commissions by connecting property owners with prospective buyers and tenants.
A newer category of property broker is increasingly taking a more active role in transactions across Lagos and other major cities.
Rather than waiting for owners to provide properties for marketing, some brokers actively identify properties they consider undervalued, negotiate directly with owners, secure agreements and subsequently market the properties at higher prices.
Some acquire properties outright before reselling them, while others secure control or contractual interests in properties and seek buyers before transactions are completed.
Others specialise in distressed properties, land in emerging locations, off-plan developments or properties that can be renovated and repositioned at a higher market value.
The model is essentially built around acquiring or controlling an asset at one price and exiting at a higher price.
That creates a different incentive structure from the traditional commission-based agency model.
Markups Can Influence Subsequent Asking Prices
The potential returns help explain the growing attraction of the model.
Under a conventional agency arrangement, an estate agent could earn a commission from facilitating a ₦100 million property transaction.
Under a brokerage or flipping model, an intermediary who acquires a property for ₦85 million and resells it for ₦100 million could potentially earn ₦15 million before accounting for transaction, financing and holding costs.
The incentive therefore extends beyond completing a transaction. It also encourages brokers to identify properties that can be acquired cheaply, controlled and resold at a premium.
The effect can become more pronounced when subsequent sellers and buyers use previous asking or resale prices as benchmarks.
For example, a property initially available for ₦90 million could be resold for ₦105 million or ₦110 million without significant physical improvement. A subsequent seller may then use the higher transaction as a reference point when setting a new asking price.
This can create successive layers of mark-ups across a market.
However, the distinction between asking prices and completed transaction prices remains important.
Limited Transaction Data Complicates the Market
Nigeria's property market has limited reliable data on actual transaction prices, making it difficult to establish precisely how much of recent price growth reflects genuine market value and how much comes from repeated price expectations.
Market reports frequently rely on asking prices, while actual completed transactions may occur at different values.
This creates information gaps between property owners, brokers, investors and buyers.
It can also make it easier for rising advertised prices to become benchmarks for subsequent transactions, even where the underlying evidence of completed sales is limited.
Greater access to reliable transaction data could therefore improve valuation, price discovery and transparency across the market.
Lagos Land Prices Show the Scale of Appreciation
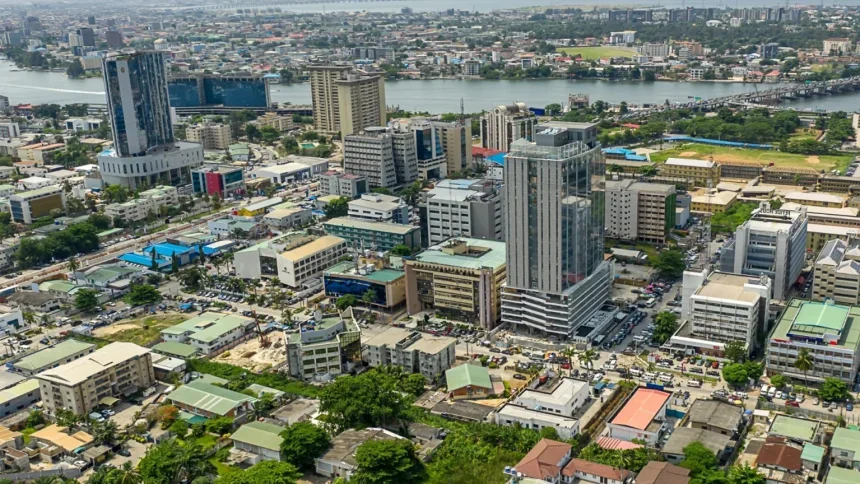
The issue has become particularly visible in Lagos, where some locations have recorded substantial increases in land values.
The 2026 Lagos Real Estate Industry Report by Agusto & Company estimated that land prices within five kilometres of the Lekki-Epe corridor increased by between 25 and 40 per cent between the first quarter of 2025 and the first quarter of 2026.
In Ibeju-Lekki, land prices reportedly increased from about ₦15 million per plot in 2024 to as much as ₦35 million in 2026.
The coastal property market has recorded even more pronounced appreciation in some locations.
Data cited for the Bluewater-Okunde area showed land values rising from approximately ₦329,000 per square metre in 2021 to between ₦2.5 million and ₦2.8 million in 2026.
Such appreciation can attract investors seeking capital gains and reinforce expectations of further price increases.
Major infrastructure and investment projects around emerging locations can also contribute to genuine increases in land values, making it difficult to separate productive investment from purely speculative activity.
Industry Divided Over Brokers' Influence
Property professionals have differing views on how much responsibility brokers should bear for rising prices.
Dr Adeniyi Tinubu, Vice Chairman, International, of the Association of Estate Agents in Nigeria (AEAN), said brokers contribute to the rapid increase in Lagos property prices but described them as “price amplifiers” rather than the fundamental price-setters.
He identified land scarcity, inflation and exchange-rate pressures as major underlying forces behind the market's price increases.
Tinubu said brokers can nevertheless accelerate price growth through expectation-driven pricing, where asking prices are influenced by the prices at which neighbouring properties are being advertised rather than the prices at which they actually sell.
Multiple agency commissions, information gaps between property owners and buyers and expectations of future appreciation can further contribute to the trend.
He also distinguished between property flipping and land speculation.
According to him, flippers can have a more direct effect on prices, while speculative land holding can be particularly significant because investors may acquire land primarily in anticipation of future appreciation rather than immediate development.
Productive Investment Versus Speculation
Tinubu cautioned against treating all property investment as harmful to the housing market.
Speculative capital can provide early-stage funding for developers, support the formalisation of land, accelerate infrastructure and development, improve distressed properties and increase liquidity.
The distinction, he argued, lies between investment that contributes to the productive use of property and activity focused primarily on extracting gains from price movements.
An investor who purchases an off-plan property and eventually develops, rents or occupies it contributes to the supply of usable housing.
By contrast, an investor who holds scarce land without development and later resells it at a substantial premium adds less directly to housing supply while potentially increasing acquisition costs for the eventual user.
Short-Lets Add Another Dimension
The expansion of short-let apartments is creating another layer of complexity, particularly in Lagos.
Residential properties are increasingly being assessed not only according to their conventional rental value but also according to their potential income from short-term occupants.
The Lagos Short-let Market Report 2025 by Edala Development estimated that the city's short-let market generated approximately ₦281.03 billion in revenue during 2025.
The report was based on 5,806 listings and projected revenue of approximately ₦285.5 billion for 2026.
It also estimated that short-let properties can generate returns between three and six times those of conventional residential leases.
The difference in potential returns creates an incentive for property owners and investors to convert conventional residential units into short-let accommodation.
This can influence the value investors place on properties in areas such as Lekki, Victoria Island, Ikoyi, Ikeja, Yaba and Surulere.
In Banana Island, the average short-let rate reportedly reached about ₦329,000 per night in 2025.
Such earning potential can encourage investors to value apartments according to their short-let revenue potential rather than conventional rental income.
Short-Lets and Rental Supply
The growth of short-let accommodation also raises questions about the supply of conventional rental housing.
Every residential property converted from long-term rental accommodation into short-let use potentially reduces the number of homes available to households seeking conventional leases.
Industry stakeholders have raised concerns about this trend in Lagos and other major cities, arguing that conversions can contribute to pressure on rental supply.
However, AEAN National Chairman Olugbenga Ismail cautioned against attributing broad rental increases solely to short-lets without stronger empirical evidence.
He acknowledged that landlords and investors have converted conventional rental properties into short-lets because of potentially higher returns and different tenancy-risk considerations.
But he stressed that the relationship between short-lets and rising rents is more complex than assuming that an increase in short-let properties automatically causes rents across an entire city to rise.
Technology Is Changing the Brokerage Market
Digital platforms are also changing the way property brokers operate.
Online listing platforms, social media, digital advertising, mapping tools and messaging applications allow brokers to market properties to large audiences almost instantly.
These tools can improve access to information and make property transactions more efficient.
They can also intensify competition for desirable properties.
Brokers can circulate listings through social media and WhatsApp groups, generate multiple expressions of interest and create a perception of scarcity or urgency around particular properties.
Where buyers compete against one another based largely on advertised prices, such dynamics can contribute to upward pressure on asking prices.
Experts Point to Rising Development Costs
Not all industry professionals agree that brokers and speculators are the main drivers of higher property prices.
Abiodun Adelaja, Chairman of the Lagos State Chapter of AEAN, attributed much of the increase to rising construction costs and broader inflation.
Landlords and developers, he said, have to price properties against prevailing costs, making it increasingly difficult to sell or rent homes at prices comparable with previous years.
The cost of cement, steel, labour, diesel, imported materials, financing and infrastructure all feed into the economics of property development.
These costs mean that even where speculative activity is limited, developers may still need to charge higher prices to recover their investment.
Adelaja called for measures to reduce construction costs and greater government intervention through public housing schemes that can provide more affordable alternatives to privately developed estates.
Market Supply Remains the Longer-Term Issue
AEAN National Chairman Ismail said speculation can amplify an already rising market but argued that the long-term solution lies in expanding housing supply.
Where properties or plots are repeatedly resold without development or value addition, each transaction can introduce another layer of expected profit.
This becomes more significant in emerging locations where investors buy land or properties primarily on the expectation that another buyer will eventually pay more.
When speculative demand begins to outpace housing production, genuine homebuyers can find themselves competing not only with other households but also with investors seeking capital appreciation.
Ismail said greater transparency, stronger professional standards, better market data and increased housing supply would be more effective responses than direct price controls.
What the Trend Means for Housing Affordability
The debate over brokers, flipping and short-lets ultimately points to a wider affordability problem.
Nigeria's housing challenge cannot be attributed to a single category of market participant.
Land scarcity, construction costs, financing conditions, infrastructure deficits and inflation can increase the underlying cost of housing, while speculative investment, repeated mark-ups and short-let conversions can influence how properties are priced and used in particular markets.
For buyers, the combination can make homeownership increasingly difficult.
For renters, higher property values can feed into rental expectations, while reduced conventional rental supply in some locations can intensify competition for available units.
For developers and investors, however, rising prices can also signal strong demand and create opportunities for new housing models, provided development remains aligned with the purchasing power of the target market.
Conclusion
Nigeria's rising property prices reflect a combination of structural costs and market behaviour.
Property brokers, flippers and speculative investors can influence pricing by adding mark-ups, benchmarking against rising asking prices and holding assets in anticipation of future appreciation. Short-let accommodation can also change the economics of residential properties and, in some locations, reduce the stock available for conventional rental use.
At the same time, industry professionals stress that these activities operate within a market already under pressure from rising land, construction, financing, infrastructure and operating costs.
The central challenge for Nigeria's housing market is therefore broader than the activities of brokers alone. Expanding housing supply, reducing development costs, improving transaction data, strengthening professional standards and increasing transparency will be critical to creating a market where investment can grow without further widening the gap between property prices and household incomes.
READ MORE