Nigeria’s ₦4.65tn Bank Recapitalisation Raises Expectations for More Productive Lending
CBN shifts focus to productive bank lending
Nigeria’s banking sector has entered a new phase after 33 banks met the revised minimum capital requirements and collectively raised ₦4.65 trillion, with the Central Bank of Nigeria (CBN) now shifting attention from capital mobilisation to how the stronger balance sheets are used.
The apex bank says recapitalisation should not be assessed solely by the amount of capital raised. Instead, banks are expected to strengthen governance, manage risks more effectively and increase lending to viable productive activities, including infrastructure and industrial projects.
/ You Might Also Like /
For Nigeria’s property and housing market, the shift is significant because access to long-term bank financing remains an important constraint on both housing supply and infrastructure development.
Recapitalisation Moves Into Its Next Phase
The two-year recapitalisation programme, announced in March 2024, required banks to strengthen their capital positions.
According to the CBN, 33 banks had met the revised minimum requirements by the end of the programme, collectively raising ₦4.65 trillion.
The increase provides banks with greater capacity to absorb losses and potentially expand their lending activities.
However, the CBN's latest position makes clear that raising capital is not the final objective. The regulator now wants stronger balance sheets to support better-quality lending and broader economic activity.
CBN Shifts Focus to Productive Lending
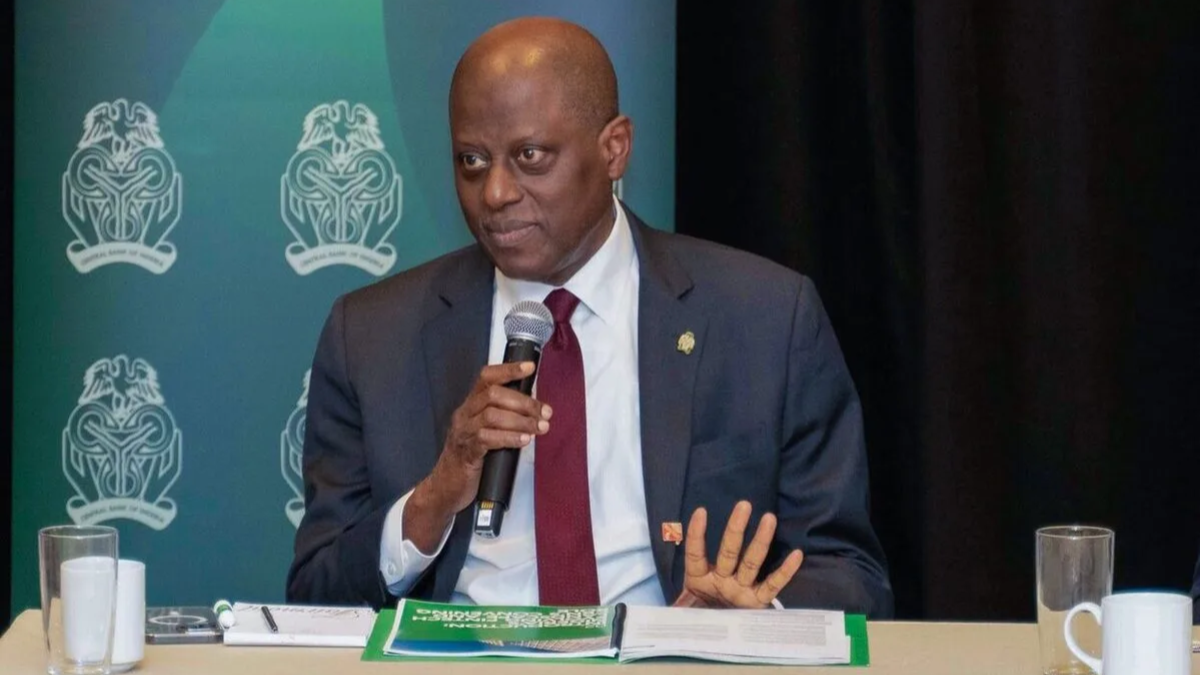
CBN Deputy Governor Muhammad Sani Abdullahi said the success of recapitalisation should be judged by the quality of banking services and productive lending supported by the additional capital.
The central bank expects stronger banks to finance long-term infrastructure, support industrial expansion, facilitate trade and improve their ability to compete in regional and international markets.
This represents an important transition for the banking industry.
The first phase focused largely on whether banks could meet higher capital thresholds. The next phase is about whether that capital can be deployed without creating excessive credit or financial-system risks.
Infrastructure Finance Could Benefit From Stronger Bank Balance Sheets
Infrastructure projects often require substantial amounts of capital over extended periods, making the availability of long-term financing particularly important.
The CBN has specifically identified infrastructure as one area where stronger bank capital should support increased financing.
For Nigeria, this could have implications for roads, power, transport, industrial infrastructure and other projects that underpin economic and property development.
Infrastructure investment can also create secondary effects for real estate by improving connectivity and making new locations more viable for residential, commercial and industrial development.
Housing Finance Remains a Separate Challenge
While stronger bank capital could increase lending capacity, recapitalisation does not automatically translate into cheaper mortgages or more affordable housing.
NHM's recent reporting has highlighted that the September reduction in the CBN's Monetary Policy Rate to 23% has yet to translate fully into lower commercial lending rates.
This distinction is important.
Banks may have more capital available after recapitalisation, but the cost of that capital, credit risk, inflation expectations, deposit costs and the maturity of available funding will continue to influence the rates charged to borrowers.
For developers, expensive construction finance can raise project costs and reduce the number of projects that are commercially viable.
For prospective homeowners, high mortgage rates can reduce borrowing capacity even when banks have greater lending capacity.
Recapitalisation Could Support Longer-Term Property Finance
One potential benefit of stronger bank balance sheets is greater capacity to participate in longer-term financing.
Property development requires substantial upfront capital for land, infrastructure, construction materials and labour. Projects can also take several years before generating sufficient cash flow.
A banking system with stronger capital buffers could potentially accommodate more long-term lending, provided banks can manage the associated risks.
This could support financing for residential developments, commercial property, industrial estates and infrastructure-linked real estate.
However, the extent of this impact will depend on individual banks' lending strategies and the availability of suitable long-term funding structures.
Risk Management Becomes the Next Test
The CBN has also placed strong emphasis on governance and risk management.
The regulator said stronger capital positions could still be undermined by poor governance or excessive risk-taking. Banks are therefore expected to strengthen internal controls and improve their management of credit, market, liquidity and operational risks.
The CBN also intends to increase its focus on risks associated with cybersecurity, third-party dependencies and climate-related financial exposures.
For property lending, stronger risk management is particularly relevant because real estate loans can have long maturities and may be affected by changes in property values, construction costs, interest rates and borrowers' cash flows.
Stronger Banks Do Not Automatically Mean More Affordable Credit
The recapitalisation has increased the financial capacity of the banking sector, but the effect on borrowers will depend on how banks choose to deploy that capacity.
This is particularly important given NHM's recent reporting that commercial lending rates remain significantly above the CBN's 23% policy rate despite the September rate cut.
The combination of stronger bank capital and high borrowing costs therefore creates an important policy question: will the additional capacity result primarily in larger balance sheets, or will it translate into greater access to appropriately priced credit for productive sectors?
Implications for Nigeria’s Housing Market
For the housing market, the most significant potential impact lies in the availability of longer-term development and mortgage finance.
If banks increase lending to viable housing projects, developers could gain access to additional construction and infrastructure finance. Greater availability of mortgage credit could also expand the pool of households able to purchase completed homes.
But financing alone cannot resolve Nigeria's housing constraints.
Land costs, infrastructure deficits, building-material prices, electricity costs, construction capacity and household incomes will continue to influence housing affordability and supply.
The banking-sector reforms therefore represent one component of a much broader housing-finance challenge.
Outlook
Nigeria's banking recapitalisation has produced ₦4.65 trillion in additional capital across 33 banks, but the CBN is now moving the conversation beyond capital adequacy.
The next phase will centre on whether stronger balance sheets support productive lending while banks maintain sound governance, asset quality and risk management.
For Nigeria's property sector, the outcome could influence the availability of development finance, infrastructure funding and mortgage credit. The key measure will ultimately be how much of the banking sector's expanded capacity reaches viable long-term investments across the real economy, including housing and infrastructure.
READ MORE