Africa Launches AfCRA as High Borrowing Costs Put Infrastructure Finance Under Pressure
Africa’s New Credit Rating Agency Could Reshape Access to Capital
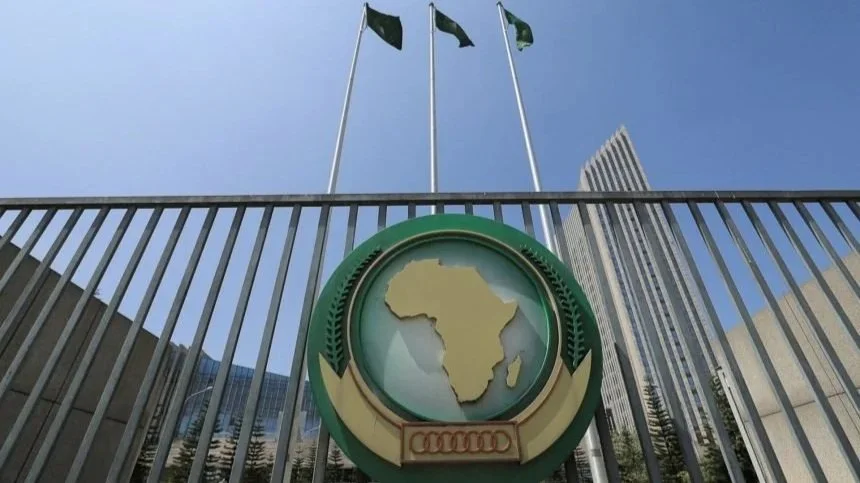
Africa has officially launched its first continent-wide credit rating agency, creating a new financial institution designed to provide additional assessments of African economies, companies and financial institutions as governments across the continent face mounting borrowing costs.
/ You Might Also Like /
The Africa Credit Rating Agency (AfCRA) was formally launched in Port Louis, Mauritius, on October 7 after years of development under the African Union and African Peer Review Mechanism.
The agency will assess sovereign borrowers, financial institutions and private companies, offering investors an Africa-focused perspective alongside established global rating agencies such as S&P Global Ratings, Moody’s and Fitch.
The African Union says the initiative is not intended to replace existing international agencies or guarantee favourable ratings. Instead, it aims to strengthen the quality and depth of information available to investors by incorporating African data, expertise and economic conditions more directly into credit assessments.
AfCRA Targets Africa’s High Cost of Capital
The launch comes against a backdrop of rising debt-servicing pressures across African economies.
The African Union said Africa’s annual external debt service increased from $61 billion in 2010 to $163 billion in 2024. In several countries, interest payments have also risen to levels that compete with spending on major public services.
Credit ratings play an important role in determining how investors perceive sovereign and corporate risk. Higher perceived risk can translate into higher interest rates, making it more expensive for governments and businesses to raise funds.
AfCRA is therefore expected to provide another source of analysis for investors assessing African markets.
The AU estimates that African economies currently average ratings around B to B-minus, compared with an average of BB for other emerging regions. It also said 23 African economies do not currently have ratings from the three major global agencies.
Independence Will Determine AfCRA’s Credibility
Despite the political support behind AfCRA, its ability to influence international capital markets will depend heavily on whether investors regard its assessments as independent and technically credible.
The AU has stressed that the agency must operate independently, maintain transparent methodologies and meet internationally recognised standards.
African Union Commission Chairperson Mahmoud Ali Youssouf said AfCRA should not be viewed as an institution designed to shield African borrowers from scrutiny or produce favourable ratings.
Instead, its value will depend on whether its assessments provide investors with reliable information about the actual risks and opportunities within individual African economies.
That distinction will be particularly important when African economies experience financial stress.
Reuters reported that rating experts have warned that AfCRA's credibility will ultimately be tested during periods of market turbulence, when investors are most likely to scrutinise whether its ratings remain independent and evidence-based.
What AfCRA Could Mean for Infrastructure Finance
The implications extend beyond sovereign debt markets.
Infrastructure projects require substantial long-term capital, while higher financing costs can affect the viability of roads, power projects, transport networks, industrial facilities and urban development schemes.
The African Union has specifically linked credit assessments to the ability of countries to finance infrastructure, energy, industrialisation and other development priorities.
For African governments and private-sector developers, a more diversified credit-rating environment could provide additional information for investors and lenders when evaluating projects and markets.
However, AfCRA's establishment does not automatically mean lower interest rates.
Its potential impact will depend on whether international investors, commercial banks, development finance institutions and other capital providers incorporate its assessments into their investment and lending decisions.
Housing and Real Estate Could Benefit From Cheaper Capital
The development is also relevant to Africa's housing markets, where access to affordable long-term finance remains one of the biggest constraints on supply.
Housing developers depend on construction finance, mortgage markets and institutional investment to deliver projects at scale. When the cost of capital rises, developers face higher financing expenses, while mortgage lenders may pass those costs on to homebuyers.
This can make already expensive housing even less affordable.
A stronger African credit infrastructure could therefore have an indirect impact on housing if it contributes to improved investor confidence, deeper capital markets and lower financing costs over time.
For Nigeria, this could matter particularly for large housing developments, mortgage finance, infrastructure-linked real estate projects and other capital-intensive investments.
But the impact should not be overstated. Land costs, infrastructure deficits, construction materials, weak household purchasing power and limited mortgage penetration remain structural barriers that a credit-rating agency cannot resolve on its own.
Nigeria Could Gain From a Broader African Financing Framework
Nigeria already has significant exposure to international capital markets and remains one of Africa's largest economies and debt issuers.
The country has also experienced changes in its sovereign credit outlook in recent years, with international rating agencies assessing the effects of foreign-exchange reforms, fiscal measures, debt dynamics and economic growth.
AfCRA could give investors another analytical reference point when evaluating Nigeria alongside other African markets.
For the Nigerian housing and real estate sectors, the more important question will be whether improvements in the broader investment environment eventually translate into greater availability of long-term capital.
That could support financing for housing construction, infrastructure and urban development if accompanied by stronger domestic financial institutions and appropriate housing-finance policies.
Africa Seeks Greater Influence Over Its Financial Narrative
The launch of AfCRA forms part of a broader effort to strengthen Africa's financial architecture and increase the continent's influence over how its economies are assessed.
The African Union has argued that greater use of African data and expertise can help address information gaps and provide more context when evaluating sovereign and corporate risk.
However, the agency will still operate within global capital markets, meaning investor acceptance will ultimately determine its influence.
Its ratings will need to demonstrate consistency, transparency and analytical independence before they can materially affect the pricing of African debt and investments.
Outlook
AfCRA's launch marks an important development in Africa's financial architecture, but its significance will ultimately be measured by market acceptance rather than the symbolism of its creation.
If the agency establishes a credible track record, expands credit coverage and earns the confidence of global investors, it could provide African governments and businesses with an additional platform for demonstrating their creditworthiness.
For housing and infrastructure markets, the longer-term opportunity lies in whether a stronger and more diversified African capital-market system can help reduce financing constraints.
For now, AfCRA begins with a substantial challenge: proving that an Africa-focused credit-rating institution can combine local economic understanding with the independence and analytical discipline required by global investors.
READ MORE