Beyond Bank Loans: How Developers Can Unlock Capital for Nigeria’s Housing Market
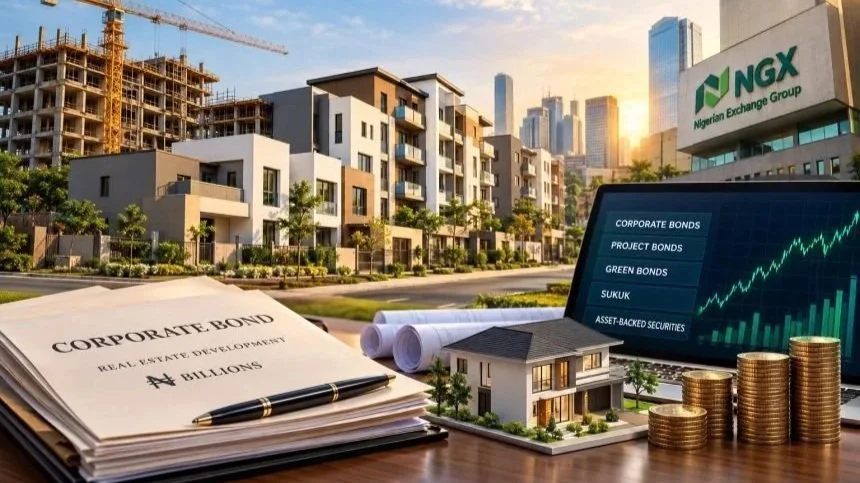
Capital-market financing could help developers fund large-scale housing projects
Nigeria’s real estate developers are being encouraged to explore capital-market financing as an alternative to relying heavily on commercial bank loans, personal savings and advance payments from prospective homebuyers to fund housing projects.
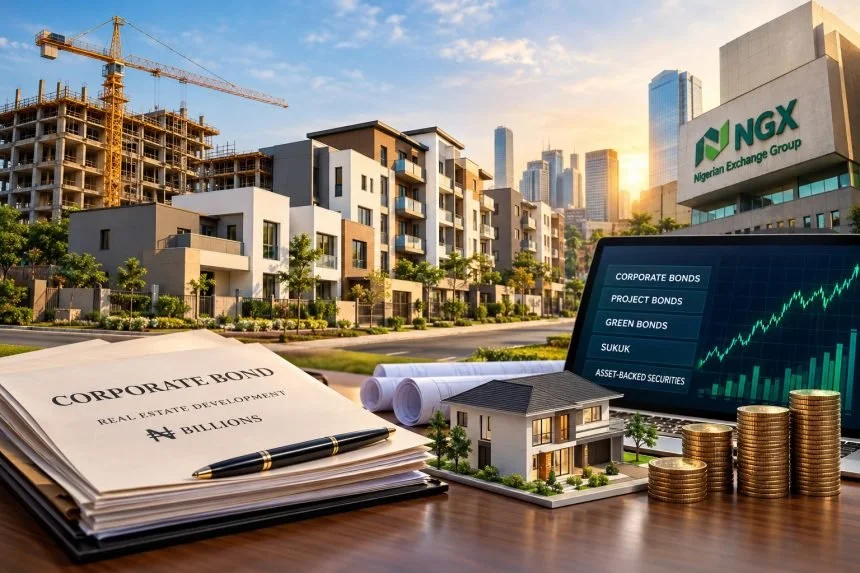
The Africa International Housing Show (AIHS), in an article published by Housing TV Africa on 11 October 2026, identified corporate bonds, project bonds, green bonds, Sukuk and asset-backed securities as potential funding instruments for eligible real estate companies.
/ You Might Also Like /
The proposal addresses a structural challenge in housing development: projects require substantial upfront investment in land, roads, drainage, electricity, water and construction, while developers often struggle to secure affordable, long-term financing.
Corporate Bonds Offer an Alternative to Bank Borrowing
Corporate bonds allow eligible companies to borrow from investors under agreed terms, including interest payments where applicable and repayment of principal.
For real estate developers, this can provide access to a wider pool of capital without necessarily surrendering ownership of their businesses, as would generally happen with equity financing.
The AIHS article illustrates the approach with a hypothetical developer seeking ₦10 billion to construct a housing estate. Rather than relying exclusively on bank credit, the company could consider issuing a bond, subject to investor demand, regulatory requirements and its capacity to repay the funds.
Repayment could depend on proceeds from property sales, rental income, other corporate revenues or dedicated project cash flows, depending on the structure.
However, bonds are not grants. They create contractual financial obligations, and developers must demonstrate that their projected income can support repayments without undermining project delivery.
Developers Have Several Capital-Market Options
The article identifies five financing instruments that could serve different types of real estate projects.
Corporate bonds: These can support business expansion, construction, refinancing and other permitted corporate purposes.
Project bonds: These are structured around specific developments, potentially including housing estates, mixed-use projects and infrastructure.
Green bonds: These can finance projects that meet recognised environmental eligibility criteria, including qualifying energy-efficient buildings and sustainable infrastructure.
Sukuk: These Sharia-compliant instruments use eligible assets and contractual structures to provide an alternative financing route.
Asset-backed securities: These allow eligible issuers to raise financing against defined pools of financial assets, potentially including qualifying mortgage receivables.
Each instrument has different eligibility, structuring and repayment requirements. Developers must assess the suitability of the funding route against their project’s scale, expected cash flows, costs and risk profile.
Stronger Governance Is Essential to Attract Investors
Accessing capital-market funding requires more than owning land or marketing a housing estate. Investors and transaction advisers need reliable information about a company’s finances, governance, assets and capacity to complete projects.
The AIHS article identifies several factors that can influence investor confidence:
Audited financial statements and transparent financial reporting.
Clear corporate ownership and effective governance.
Verifiable land titles, planning approvals and other required authorisations.
A credible record of completed projects.
Realistic financial projections and demonstrated repayment capacity.
Credit ratings, guarantees, collateral or other credit enhancements where required.
These requirements are particularly relevant in a property market where buyers can face losses when developers fail to complete projects after collecting deposits or selling units off-plan.
Capital-market scrutiny may encourage greater disclosure and financial discipline among participating companies. However, issuing bonds does not guarantee successful project delivery, and investors still face the risk of delayed construction, weak sales, cost overruns and default.
Can Smaller Developers Access Institutional Finance?
Large developers may be better positioned to meet the costs and administrative requirements of an individual bond issuance. Smaller companies may lack the scale, financial records or credit strength required to attract institutional investors independently.
The AIHS article proposes that professionally managed financing vehicles could aggregate eligible projects from multiple developers, potentially creating a route for credible medium-sized companies to access pooled funding.
Such arrangements would require independent project assessments, strong governance, transparent reporting and appropriate safeguards for investors. Pooling projects would not eliminate credit risk; each development would still need to demonstrate commercial viability and a credible repayment structure.
For smaller developers, the practical challenge is to build the financial and operational systems needed to qualify for these arrangements.
Pension Funds and Other Institutions Could Provide Long-Term Capital
Nigeria’s pension funds, insurance companies and other institutional investors manage substantial pools of savings that could potentially support suitable housing investments through eligible capital-market instruments.
For housing developers, this presents a possible alternative to short-term borrowing for projects that require several years to complete and generate revenue.
However, institutional funding is not automatically available to every property company. Pension fund investments must comply with applicable National Pension Commission requirements, while other institutional investors must follow their own mandates, risk limits and regulatory obligations.
The Securities and Exchange Commission also maintains rules governing the registration and offering of securities. Developers must work with appropriately registered capital-market professionals to determine the permissible structure and applicable requirements for each transaction.
Housing projects must compete with other investment opportunities on risk, return, liquidity and regulatory eligibility. Developers therefore need credible projects and financing terms that can attract investors without placing unsustainable repayment obligations on the business.
Long-Term Funding Could Address a Structural Housing Challenge
Housing development requires substantial investment before homes can be sold or rented. Developers must often finance land acquisition, site preparation, roads, drainage, electricity and water infrastructure before receiving sufficient revenue from completed units.
Dependence on short-term borrowing can create a mismatch between financing obligations and the time required to finish and sell a project. Advance payments from homebuyers can also expose developers to pressure when construction costs rise or sales slow.
Properly structured long-term capital-market financing could help address this mismatch by aligning funding with the development’s expected cash flows.
Nevertheless, the cost of issuing bonds, interest or coupon payments, professional fees and other transaction expenses could make the financing expensive. If developers pass those costs on to buyers, the funding model may not improve housing affordability.
The key is to secure financing on terms that match the project’s economics while preserving sufficient resources to complete and maintain the development.
Outlook
Capital-market financing offers Nigerian developers a potential route to diversify their funding sources beyond bank loans, personal savings and homebuyer deposits. Corporate bonds, project bonds, green bonds, Sukuk and asset-backed securities could support housing and infrastructure projects where the issuer, instrument and underlying cash flows meet the necessary requirements.
The opportunity, however, depends on stronger corporate governance, credible financial reporting, secure land titles, realistic project assessments and the ability to repay investors.
For Nigeria’s housing market, the objective should not simply be to raise larger amounts of money. It should be to mobilise sustainable capital that can be converted into completed homes and functioning infrastructure without creating excessive financial risks or making housing less affordable.
READ MORE