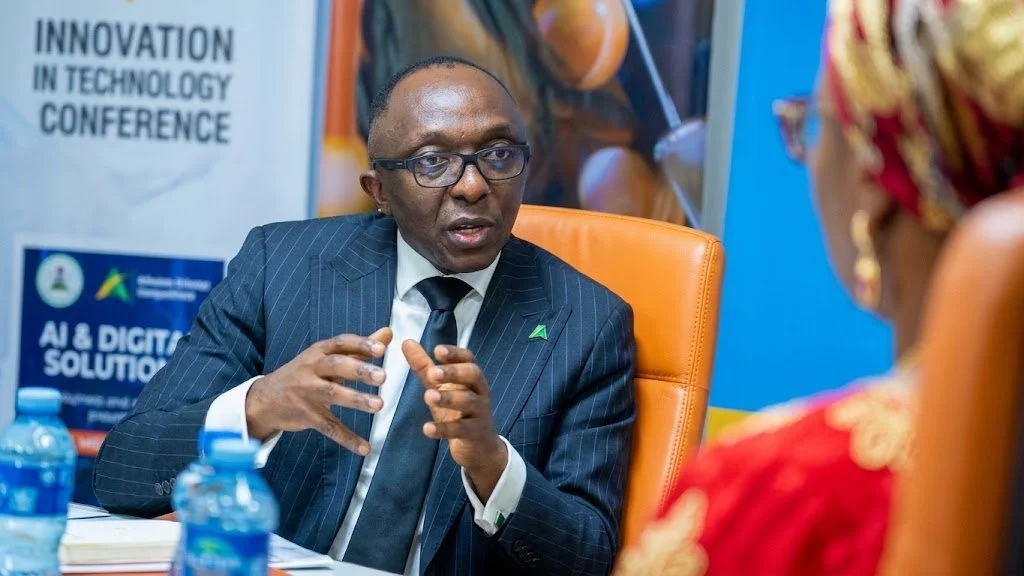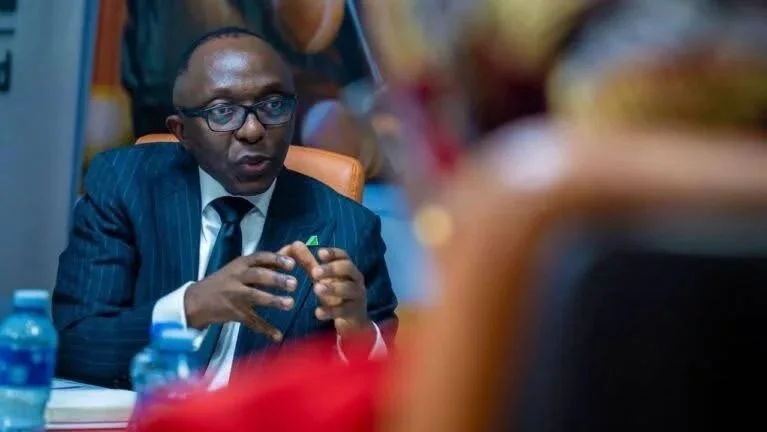
MOFI Managing Director Armstrong Takang
Fewer than 10 per cent of properties across Nigeria have proper land titles, leaving most property owners unable to fully unlock the financial value of their assets and exposing buyers and investors to ownership disputes, according to the Managing Director of the Ministry of Finance Incorporated (MOFI), Armstrong Takang.
Takang disclosed this on Monday, 2 November 2026, at a stakeholder conference organised by the House of Representatives on proposed legislation to establish a National Real Estate Regulatory Authority (NRERA)
/ You Might Also Like /

He said inadequate property documentation, weak regulatory oversight and fraudulent transactions were undermining confidence in Nigeria's real estate market and restricting the sector's ability to attract investment.
"Less than 10 percent of the properties nationwide have proper titles," Takang said, explaining that many Nigerians own properties they cannot effectively use to access credit or generate additional economic value.
The disclosure highlights a longstanding challenge in Nigeria's property market, where unclear ownership records and lengthy land registration processes have limited the use of real estate as a financial asset.
Poor Land Documentation Locks Up Property Wealth
Land titles provide formal evidence of ownership and help establish the legal rights attached to a property. They also support property transfers, financing arrangements and the use of real estate as collateral.
Without verifiable documentation, property owners can struggle to secure bank loans, attract institutional investors or complete transactions with confidence.
Takang linked the problem to Nigeria's relatively low credit penetration, noting that lending stood at approximately 12.9 per cent of Gross Domestic Product (GDP), compared with 20.1 per cent across sub-Saharan Africa and 34 per cent in lower-middle-income countries.
The absence of reliable property records limits the ability of financial institutions to verify ownership and assess the legal security of assets offered as collateral.
For developers and property investors, this creates additional risks around land acquisition, project financing and the transfer of ownership. It also restricts the potential of property to serve as an instrument for wealth creation and business expansion.
Proposed Real Estate Regulator Targets Fraud and Weak Oversight
The stakeholder conference examined a proposed bill seeking to establish the National Real Estate Regulatory Authority to strengthen oversight of Nigeria's property market.
Takang said the proposed authority would introduce standards for property transactions, establish licensing requirements for real estate agents and developers, and provide safeguards for funds paid by prospective property buyers.
He warned that weak oversight had allowed unlicensed operators to collect substantial sums from investors without delivering promised properties.
The proposed framework is also expected to address fraudulent land transactions and improve accountability among businesses operating in the real estate sector.
Chairman of the House Committee on Housing and Habitat, Abdulmumin Jibrin, said institutional gaps and overlapping responsibilities among government agencies had weakened the regulation of housing and real estate activities.
He argued that the housing minister did not exercise direct jurisdiction over every institution involved in housing delivery, creating coordination challenges that affected the sector.
Jibrin said the proposed legislation would not take over the constitutional responsibilities of state governments or the statutory functions of existing professional bodies. Instead, it would promote cooperation between federal and state authorities.
The proposed authority has not yet been established. Its eventual responsibilities, relationship with existing institutions and enforcement powers will depend on the legislative process and the final provisions of the bill.
Housing Minister Highlights Nigeria's Low Mortgage Penetration
The Minister of Housing and Urban Development, Muttaqha Darma, also identified limited mortgage access as a major obstacle to homeownership.
He put Nigeria's mortgage penetration below 10 per cent, compared with 38 per cent in Malaysia and 40 per cent in South Korea.
The figures highlight the gap between Nigeria's property ownership market and the formal housing finance systems that allow households to spread the cost of acquiring homes over extended repayment periods.
Poor land documentation compounds the challenge because lenders need reliable evidence of ownership before accepting properties as collateral.
Darma suggested that the proposed regulatory authority should operate under the Ministry of Housing and Urban Development to support coordination with existing national housing policies.
House Speaker Calls for Digitised Property Administration
Speaker of the House of Representatives, Tajudeen Abbas, called for a centralised and digitised real estate administrative system to improve transparency, simplify property transactions and strengthen investor confidence.
He argued that Nigeria's challenge was not simply a shortage of properties but a lack of trust in the systems governing ownership and transactions.
A more integrated property administration framework could improve access to ownership records, make verification easier and reduce opportunities for fraudulent transactions.
For property buyers, investors and developers, reliable digital records could help establish ownership history, verify transaction documents and improve confidence before committing funds to land or housing projects.
However, the effectiveness of such a system would depend on accurate records, coordination among state land registries and appropriate safeguards against manipulation.
What Poor Land Titling Means for Nigeria's Property Market
The low level of formal property documentation has implications beyond individual ownership disputes. It affects the wider structure of Nigeria's real estate investment market.
For developers, uncertain land ownership can delay project execution, increase due diligence costs and expose investments to litigation. Financial institutions also face difficulties accepting properties with unclear titles as security for loans.
The situation can discourage institutional investment, particularly in large-scale residential and commercial developments that require substantial financing and clear legal ownership.
Formalising property ownership could therefore help expand access to mortgage finance, improve land-market transparency and make more properties available for productive investment.
However, establishing a national regulator alone will not resolve the problem. Effective reform will also require improvements to state land administration systems, faster title registration, accessible digital records and stronger enforcement against fraudulent transactions.
For Nigeria's housing market, the central challenge is ensuring that property ownership comes with verifiable legal rights that allow owners, developers and investors to use their assets with confidence.
READ MORE