Cooperatives Seek Housing Vouchers, Guarantees to Expand Homeownership in Nigeria
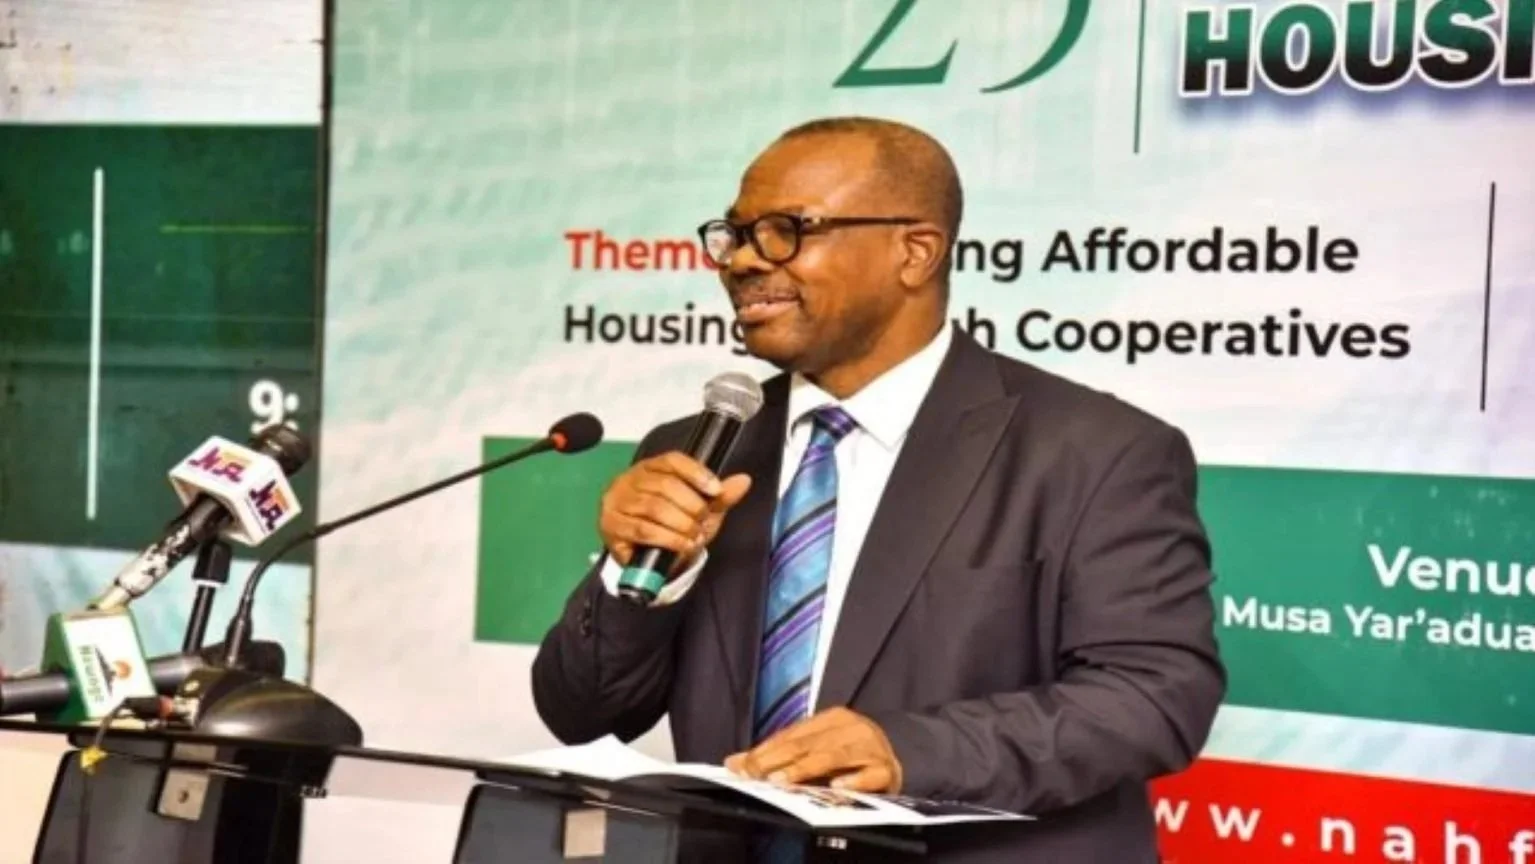
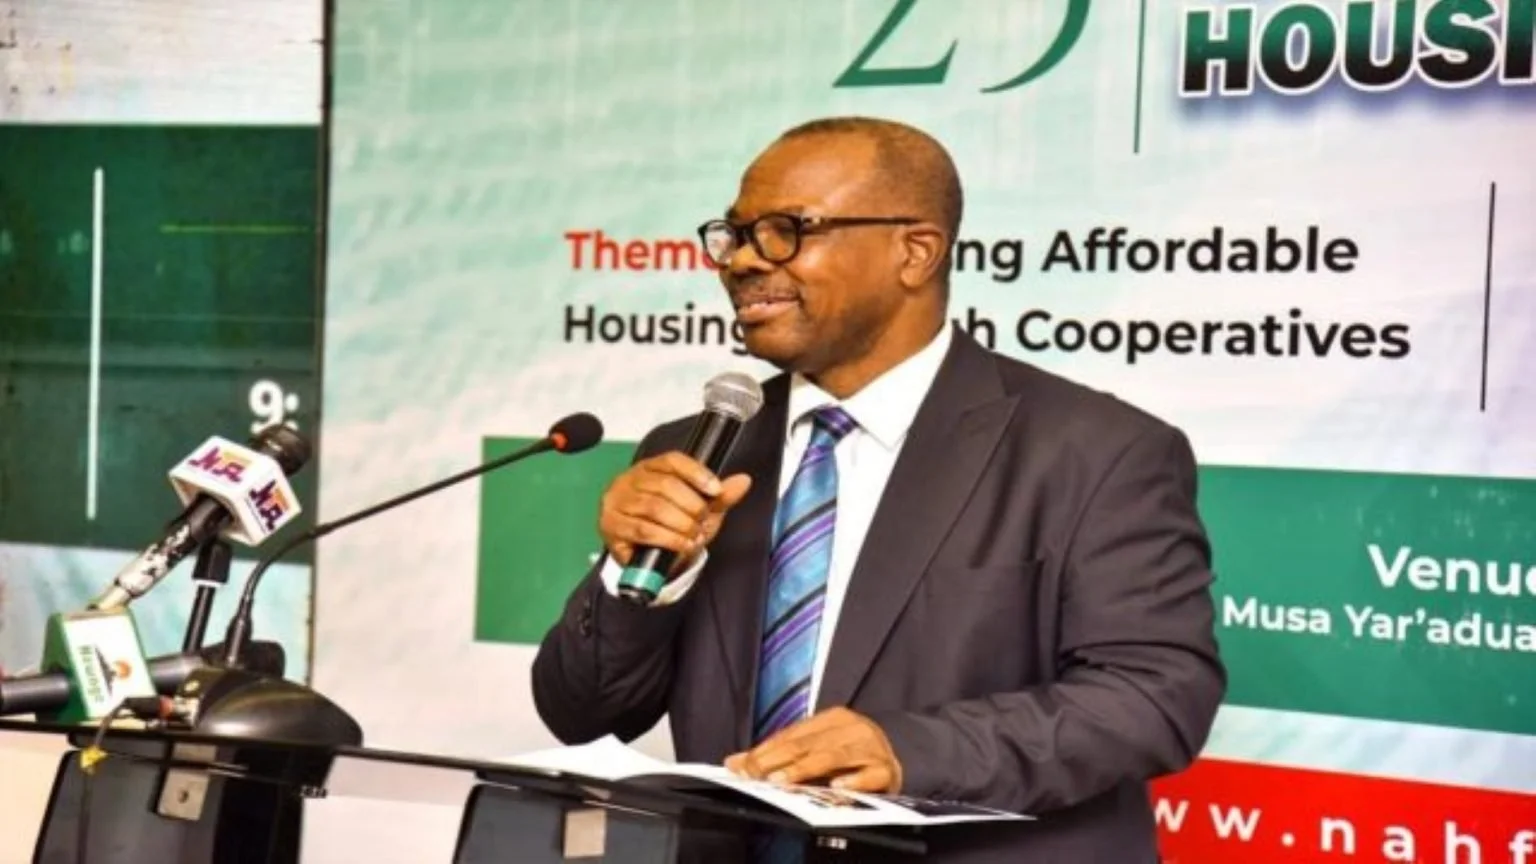
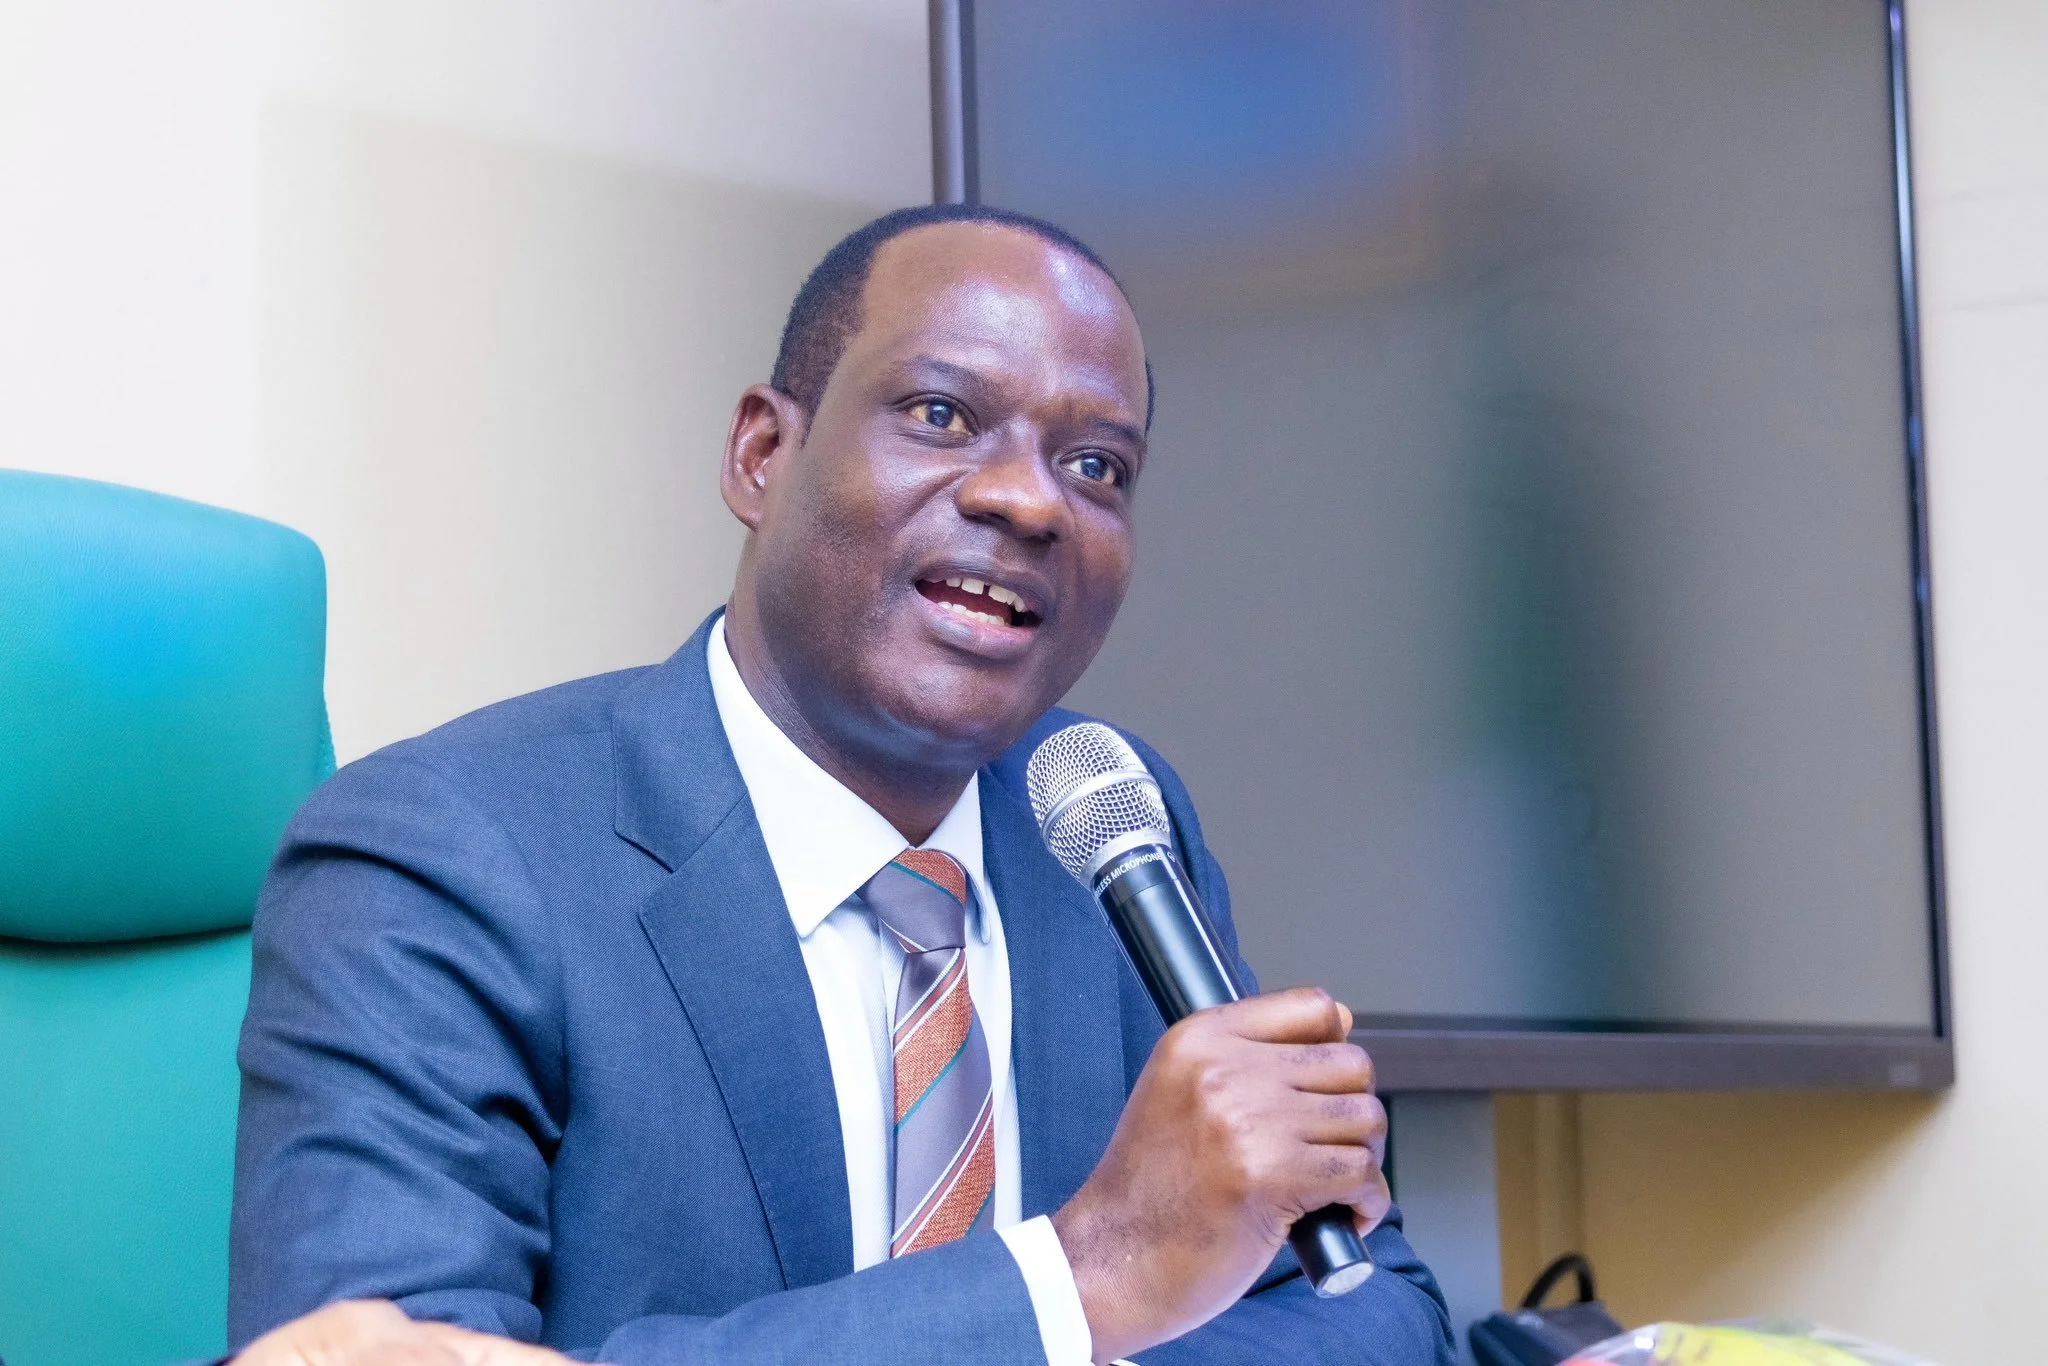
Dr Yemi Adelakun, President of the Cooperative Housing Federation of Nigeria
Nigeria’s cooperative housing sector has called for housing vouchers, credible guarantees and innovative financing arrangements to help more households buy homes, particularly workers and self-employed people who struggle to access conventional mortgages.
/ You Might Also Like /

Dr Yemi Adelakun, President of the Cooperative Housing Federation of Nigeria (COHFON), presented the proposals in a paper titled Cooperative Housing in Nigeria at the National Cooperative Summit, Expo and Awards in Abuja. He urged governments to strengthen partnerships between housing cooperatives, construction firms and financial institutions to expand access to affordable homes.
Adelakun said the proposed measures would help connect organised groups of prospective homeowners with developers and lenders, reduce reliance on intermediaries and improve the delivery of housing that buyers can afford.
Housing Vouchers and Guarantees to Support Homeownership
Adelakun called on governments to introduce housing vouchers and credible guarantee arrangements that could help prospective homeowners overcome financing barriers. He also advocated partnerships with prequalified engineering, procurement, construction and finance companies capable of delivering pre-designed homes at agreed prices.
Under the proposed approach, housing cooperatives could organise members who already own land but lack the technical capacity or financial resources to develop it. Qualified construction and finance companies would then work with these groups under agreed delivery and pricing arrangements, backed by guarantees from the cooperatives.
Such arrangements could help reduce uncertainty for developers and financiers by establishing demand before construction begins. They could also give cooperative members greater bargaining power over prices, construction quality and delivery terms.
The proposal places organised housing demand at the centre of project planning, rather than relying on developers to build homes without sufficient certainty about whether prospective buyers can afford them.
Cooperatives Push for Single-Digit Housing Finance
The federation also called for a dedicated revolving intervention fund to provide housing finance through cooperatives at single-digit interest rates. Adelakun said the initiative could build on the Federal Mortgage Bank of Nigeria’s Cooperative Housing Development Loan programme.
He acknowledged existing government-backed housing finance initiatives involving the Federal Mortgage Bank of Nigeria (FMBN), Family Homes Funds, the Federal Government Staff Housing Board and the Mortgage Refinance and Investment Fund (MREIF).
Adelakun cited financing rates of six per cent for FMBN, five per cent for Family Homes Funds, three per cent for the Federal Government Staff Housing Board and 9.75 per cent for MREIF. He argued that these initiatives needed to form part of a broader financing system capable of reaching more households.
He maintained that public institutions alone could not meet Nigeria’s housing needs, particularly because many households do not qualify for available mortgage products. He therefore urged governments to expand financing options for underserved groups and consider land equity support for affordable housing developments.
A revolving intervention fund could provide a dedicated source of finance for cooperative housing projects, although its effectiveness would depend on adequate capitalisation, clear eligibility rules, sustainable repayment arrangements and transparent management.
Informal-Sector Workers Remain Underserved
Adelakun identified limited access to conventional mortgage financing as a major obstacle for artisans, market traders, artists and other self-employed Nigerians.
Many people in these groups earn irregular incomes or lack the formal documentation lenders require to assess repayment capacity. As a result, they can struggle to qualify for mortgages even when they have the capacity to save towards a home over time.
Housing cooperatives could help address this gap by pooling members’ savings, aggregating demand and building a stronger collective financial profile. Members could contribute towards equity, acquire land jointly or individually, and participate in housing projects through approved investment arrangements.
By organising prospective homeowners before construction begins, cooperatives could also help developers better understand buyers’ budgets and housing requirements. This could reduce the risk of producing homes that fall outside the financial reach of the intended market.
Adelakun stressed that cooperative housing should extend beyond conventional savings and thrift activities. Existing multipurpose and sectoral cooperatives could partner with specialised housing cooperatives to develop structured homeownership programmes for their members.
Digital Finance and Guarantees to Strengthen Housing Delivery
COHFON is working with Proppay, a digital finance infrastructure provider for the housing ecosystem, to advance its digital finance agenda, Adelakun disclosed.
The federation also plans to support the development of cooperative digital banking linked to the proposed Cooperative Bank of Nigeria. The initiative is intended to facilitate the management of the Cooperative Housing Fund and improve the organisation of financial contributions.
Other priorities include aggregating members’ savings and equity contributions, developing credible guarantees and escrow arrangements, and establishing special-purpose vehicles to connect organised housing demand with developers and financiers.
Escrow arrangements could help protect payments by placing funds under agreed controls until specified transaction or project conditions are met. Special-purpose vehicles could also provide a structure for financing individual housing developments and managing their obligations separately.
However, these arrangements would require robust oversight, reliable financial records and clear rules for handling members’ contributions. Adelakun identified good governance, transparency, accountability, capable leadership and sound financial management as essential to building confidence in cooperative housing.
Public, Private and People Partnerships
Adelakun advocated a Public, Private and People Partnership model to coordinate the roles of government, financial institutions, developers, technology providers and communities.
Under the proposed framework, governments would provide enabling policies and infrastructure, while financial institutions would develop suitable financing products. Developers would deliver homes, and cooperatives would organise prospective buyers, mobilise savings and help establish effective demand.
He also called for stronger coordination between existing housing finance mechanisms, including the National Housing Fund and FMBN’s mortgage, construction, rent-to-own and cooperative housing products.
The objective, he said, should be to create a more integrated pathway linking savings, land acquisition, housing construction and long-term finance, rather than treating each stage as a separate challenge.
Governance Will Determine the Model’s Success
Although cooperative housing offers a way to combine individual savings and purchasing power, its effectiveness depends on the ability of cooperatives to manage funds and deliver projects responsibly.
Weak financial management, limited technical capacity and inadequate protection for members’ contributions can undermine confidence and discourage participation. Cooperatives seeking support from government and private financiers would therefore need credible governance structures, transparent procurement and clear accountability for project delivery.
Guarantees must also be designed carefully to establish who bears the financial risk if a project is delayed, a member defaults or a developer fails to meet contractual obligations. Housing vouchers would similarly require clear eligibility criteria, funding arrangements and safeguards to ensure that support reaches the intended beneficiaries.
For developers and lenders, the proposed model could offer a more organised pool of potential buyers. For households, it could create an alternative route to homeownership, provided the financing terms, house prices and repayment obligations match their incomes.
Outlook for Affordable Housing Delivery
COHFON’s proposals seek to address several interconnected barriers to homeownership: expensive credit, high construction costs, limited access to land and inadequate mortgage guarantees. By combining collective savings with targeted financing and professional housing delivery, cooperatives could help bring more underserved households into the formal housing market.
The proposals, however, require coordinated action from governments, lenders, developers and cooperative organisations. Their impact will depend on whether the proposed vouchers, guarantees and revolving fund secure adequate financing and operate under transparent, accountable systems.
For Nigeria’s housing market, the central challenge remains turning organised demand into completed homes that households can afford. A cooperative model that links credible buyers, suitable land, reliable developers and sustainable finance could help close that gap, provided it protects members’ funds and delivers housing at agreed prices.
READ MORE