Finance Minister Taiwo Oyedele says foreign exchange shortages and costly subsidy policies contributed to more than ₦30 trillion in monetary financing
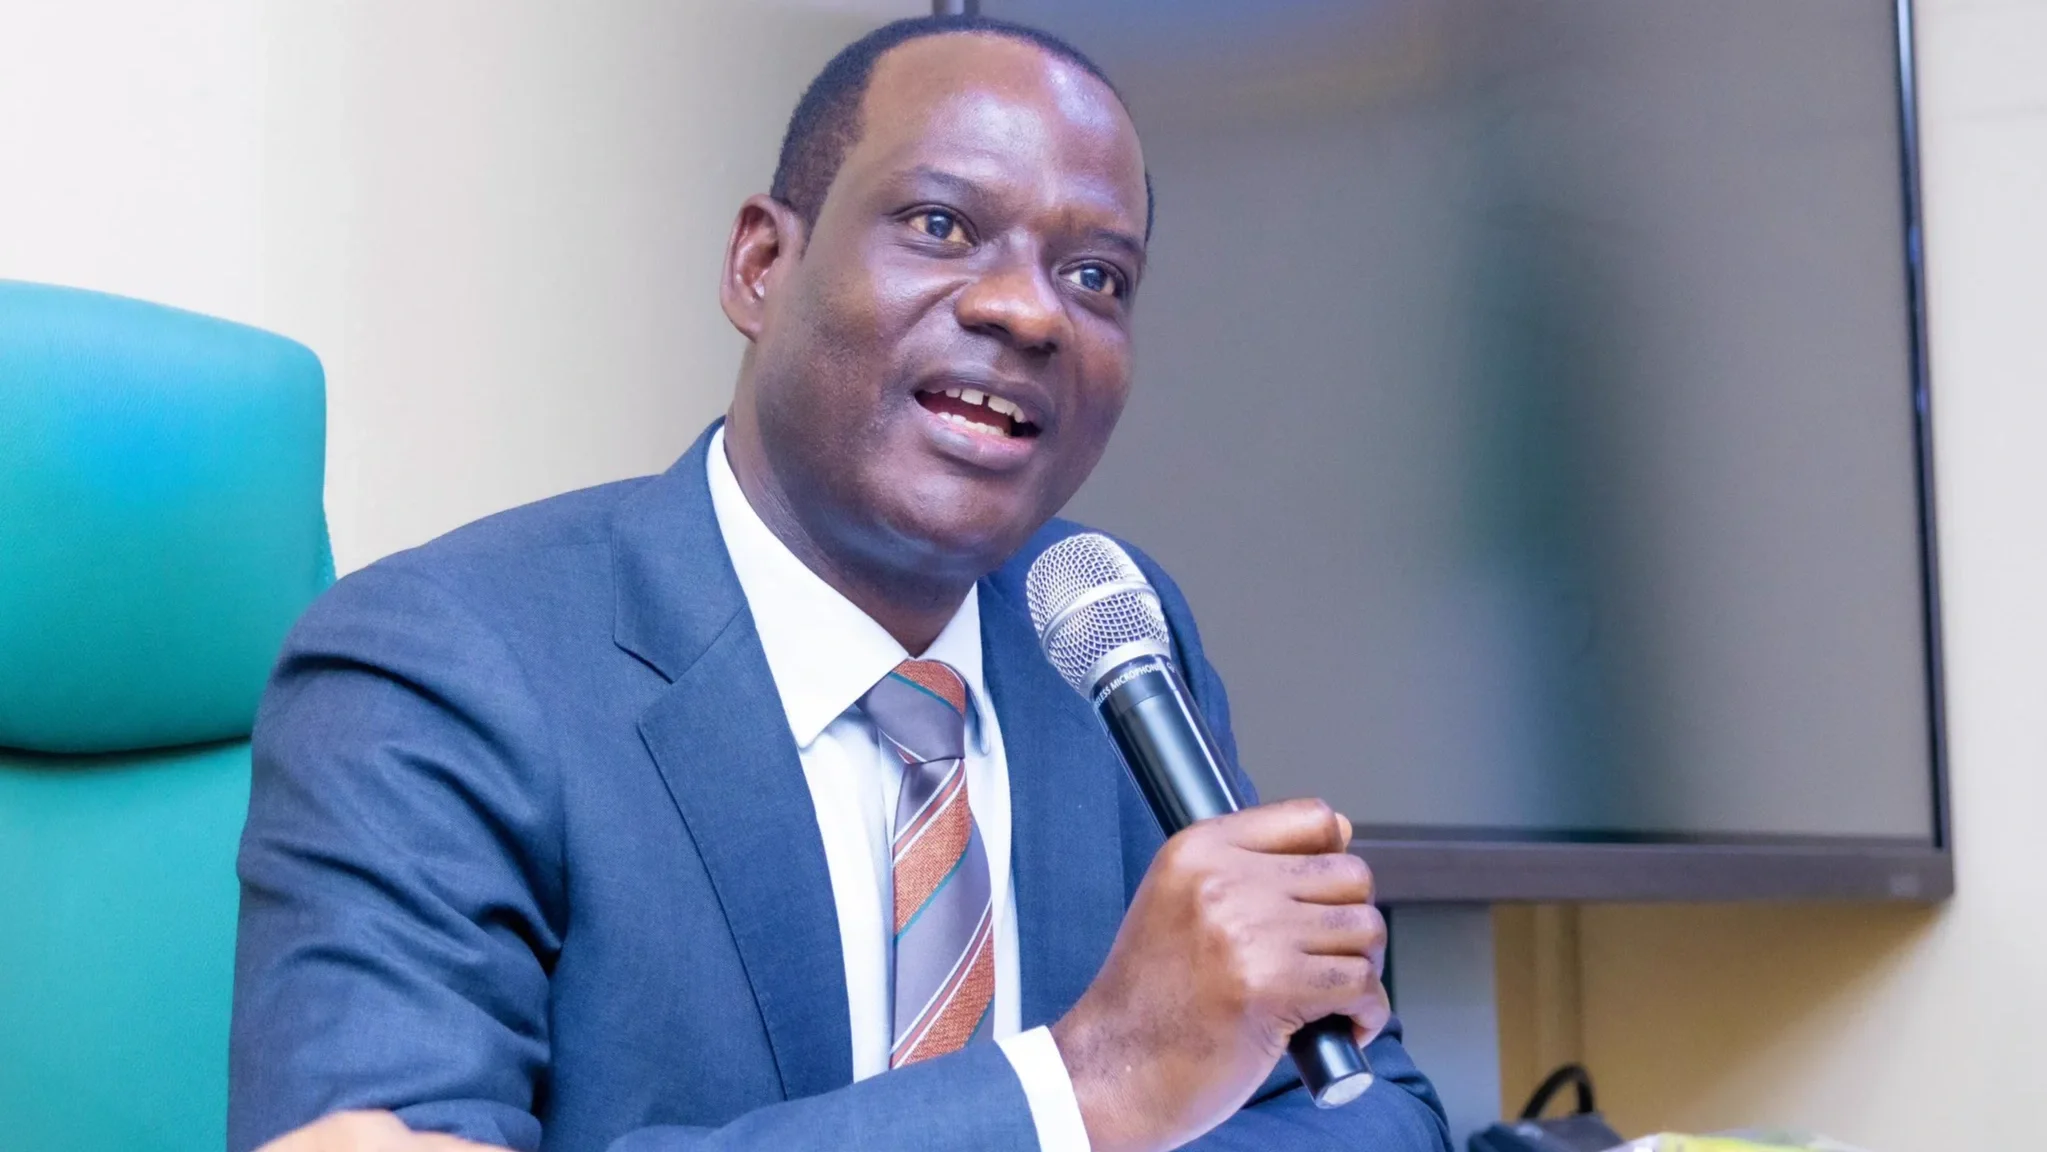
Nigeria’s Finance Minister and Coordinating Minister of the Economy, Taiwo Oyedele, has attributed more than ₦30 trillion in money creation about three years ago to severe foreign exchange shortages, declining crude oil earnings and the cost of government subsidy policies.
/ You Might Also Like /

Speaking at the 56th Annual Accountants’ Conference of the Institute of Chartered Accountants of Nigeria (ICAN) in Abuja on Tuesday, 20 October 2026, Oyedele said the country struggled to meet its foreign currency obligations, leaving businesses, individuals and international airlines unable to access or repatriate funds.
The minister linked the crisis to the economic pressures that preceded the Federal Government’s 2023 reforms, including petrol subsidy removal and changes to the foreign exchange market. He also connected excessive money creation during that period to inflationary pressures that continue to affect household purchasing power and business costs.
Foreign Exchange Shortages Disrupted Businesses
Oyedele said the shortage of foreign currency created significant difficulties for businesses that relied on international payments, imported inputs and cross-border transactions.
He explained that some young Nigerians could not use their bank cards to pay for digital services needed to work and earn income online. Manufacturers also faced difficulties because foreign suppliers had lost confidence in letters of credit issued by Nigerian banks.
Companies that managed to obtain dollars often paid substantial premiums to access them, increasing the cost of importing machinery, raw materials and other production inputs.
The minister said the restrictions also affected international airlines operating in Nigeria. Some struggled to repatriate ticket revenue and other earnings, creating uncertainty over whether they could recover funds generated from their Nigerian operations.
These conditions, he argued, reflected the depth of the foreign exchange crisis before the government's policy changes.
Subsidy Policies and Crude Oil Constraints Increased Pressure
Oyedele also blamed the former subsidy arrangements for placing a heavy burden on public finances, arguing that the system eventually strained the government's own financial resources.
He said Nigeria's limited access to crude oil revenue worsened the situation because much of the country's crude production had already been committed to existing obligations. According to the minister, less than 100,000 barrels per day remained available to the government before President Bola Tinubu intervened.
The combination of limited crude oil resources, weak foreign exchange inflows and substantial subsidy-related commitments left the government struggling to meet its financial obligations, Oyedele said.
He argued that these pressures contributed to the decision to create more than ₦30 trillion through monetary financing about three years ago.
How Money Creation Contributed to Inflation
The minister linked the past expansion of the money supply to the inflationary pressures affecting Nigeria's economy.
When a government finances expenditure through money creation, rather than relying on sufficient revenue or sustainable borrowing, additional money can enter circulation without a corresponding increase in the supply of goods and services. Under those conditions, the extra liquidity can intensify inflationary pressures.
In Nigeria, the effects of currency depreciation, higher import costs and rising fuel prices have also contributed to the cost pressures faced by households and businesses.
Oyedele has argued that the economic reforms introduced in 2023 were necessary to address these underlying imbalances. He maintained that removing the petrol subsidy and reforming the foreign exchange market helped prevent a more severe economic crisis.
However, the claim that the government could have faced inflation of up to 1,000% without the reforms remains the minister's assessment of a hypothetical scenario, rather than an observed inflation outcome.
The distinction is important when assessing the government's economic argument: the reforms were intended to address structural distortions, but their longer-term success also depends on whether inflation moderates sustainably and household purchasing power improves.
Economic Reforms and the Cost of Living
The removal of the petrol subsidy and changes to the foreign exchange market altered the cost structure facing Nigerian households and businesses.
Petrol prices increased following subsidy removal, while currency depreciation raised the naira cost of imported goods, machinery and production inputs. These changes placed additional pressure on transport operators, manufacturers, retailers and service providers.
The government has defended the reforms as necessary to improve fiscal sustainability, reduce market distortions and strengthen the economy's ability to attract investment.
Nevertheless, the transition has created significant affordability challenges. Lower inflation means prices are increasing more slowly; it does not necessarily mean that goods and services have become cheaper.
For households, meaningful relief will depend partly on whether incomes and employment opportunities grow sufficiently to offset higher living costs. For businesses, sustained improvements will require more predictable foreign exchange access, stable operating conditions and stronger domestic production.
Implications for Housing and Real Estate
Nigeria's housing and real estate sector remains exposed to the economic pressures associated with currency depreciation, inflation and high financing costs.
Foreign exchange instability can raise the cost of imported building materials, equipment and finishing products. Even locally sourced materials can become more expensive when manufacturers rely on imported machinery, spare parts or production inputs.
Inflation also affects contractors' budgets, developers' working capital requirements and the prices prospective homeowners must pay. When construction costs rise faster than household incomes, developers face greater difficulty delivering homes at affordable prices.
High interest rates can compound these pressures by increasing the cost of development finance and limiting access to mortgages. Consequently, stabilising inflation and improving foreign exchange conditions could support the housing market over time, although the benefits would also depend on infrastructure investment, land access and the availability of long-term housing finance.
The minister's account of Nigeria's past monetary financing therefore has relevance beyond public finance. It highlights how instability in the wider economy can affect investment decisions, construction costs and the ability of households to access housing.
Outlook
Oyedele's explanation has renewed attention on the relationship between Nigeria's former subsidy arrangements, foreign exchange shortages, monetary financing and inflation.
The minister maintains that the pressures contributed to more than ₦30 trillion in money creation about three years ago and argues that the subsequent economic reforms were necessary to address longstanding imbalances.
The wider test for policymakers is whether these changes can deliver lasting price stability, stronger production, improved access to foreign exchange and rising household incomes. For investors and businesses, including those in housing and real estate, sustained macroeconomic stability will be important for reducing cost uncertainty and supporting long-term investment.
READ MORE