Falling Food Prices Mask Persistent Cost Pressures Across Nigeria’s Economy
Nigeria’s lower headline inflation has yet to ease pressure across housing and household expenses
Nigeria’s headline inflation rate declined to 14.63% in September 2026, extending its downward trend for a fourth consecutive month. However, the slowdown offers only a partial picture of the cost pressures facing households, landlords, property developers and prospective homebuyers.
/ You Might Also Like /

Data from the National Bureau of Statistics (NBS) show that headline inflation fell from 15.39% in August to 14.63% in September, compared with 20.98% a year earlier. The decline coincided with a 1.55% month-on-month reduction in food prices, which helped slow the overall increase in consumer prices.
Yet underlying price movements remain a concern. Monthly core inflation, which excludes agricultural produce and energy, rose to 1.11% in September from -0.06% in August. The divergence highlights why a decline in headline inflation does not necessarily mean that the cost of living, renting a home or developing property is falling.
Food Prices Fall as Core Inflation Rises
The September figures reflect contrasting movements across major components of Nigeria’s consumer price basket.
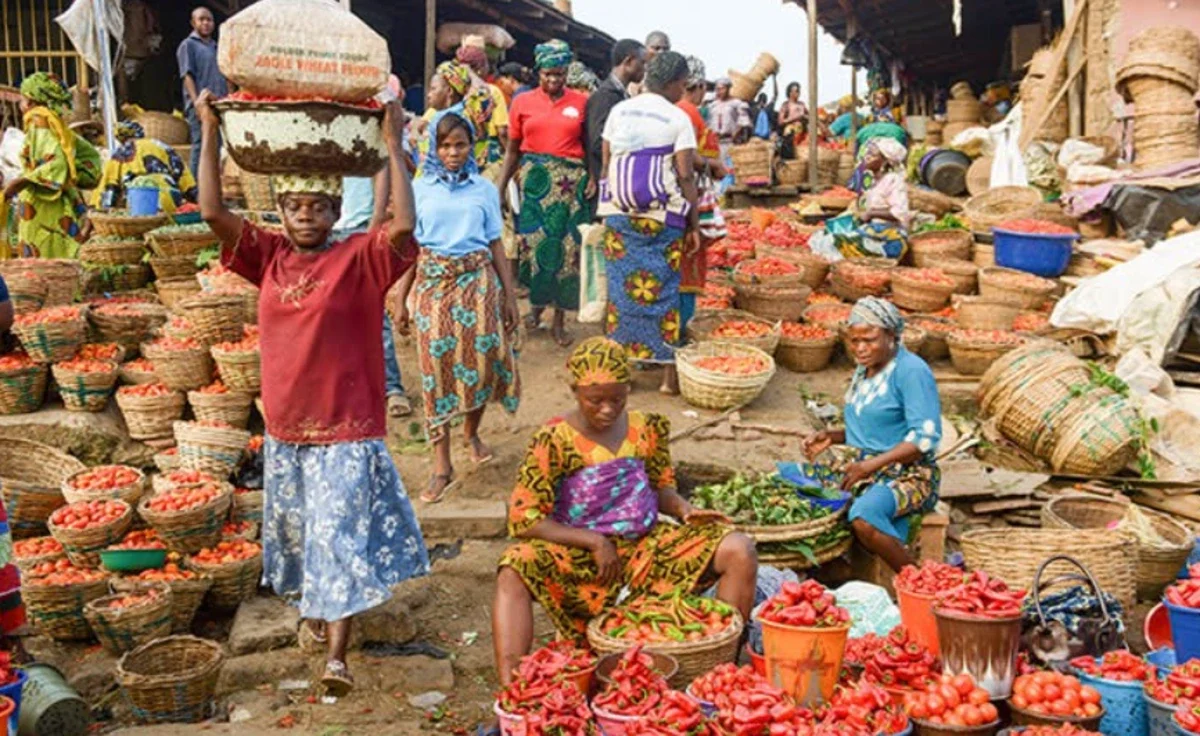
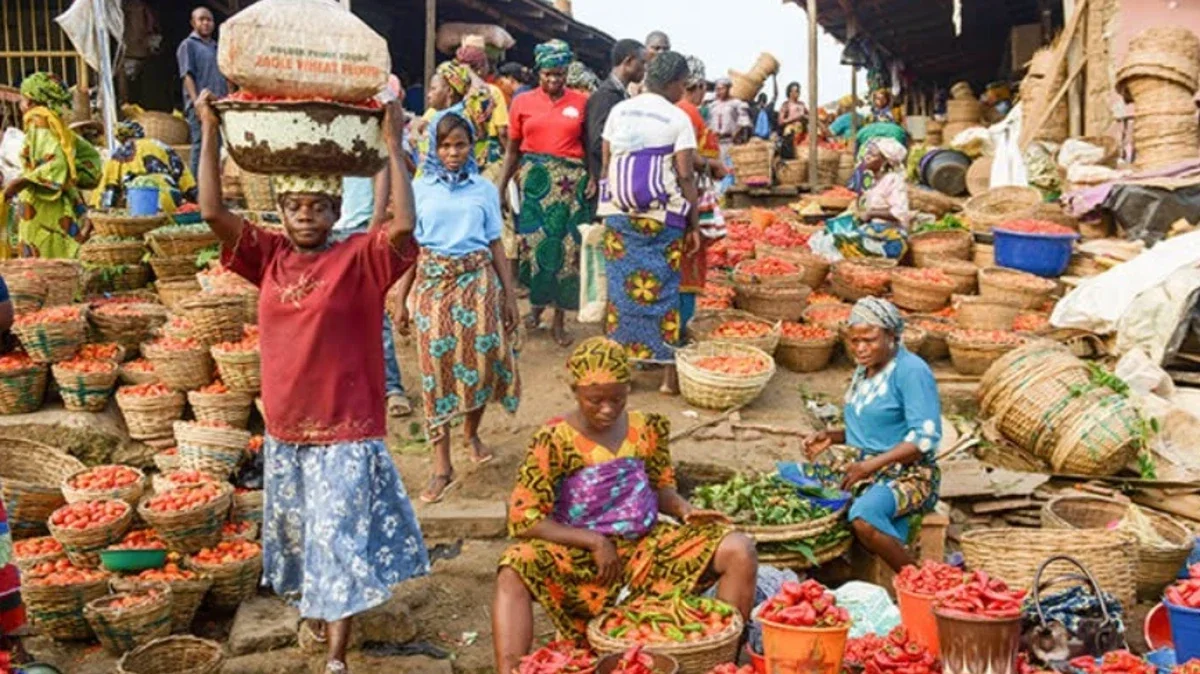
Food prices declined by 1.55% month on month, reversing the 1.02% increase recorded in August. The NBS attributed the movement to price changes in items including grains, rice, eggs, onions, palm oil, vegetables, potatoes, plantain and tomatoes.
Annual food inflation, however, remained elevated at 19.59% in September. This means that although some food prices declined between August and September, the broader food basket remained substantially more expensive than a year earlier.
Core inflation moved in the opposite direction on a monthly basis, rising to 1.11% after recording a decline in August. Its annual rate stood at 12.95%, down from 22.11% in September 2025.
The distinction matters because households face a range of expenses beyond food. Rent, transport, utilities, education and other services can continue to absorb income even when seasonal food-price declines reduce headline inflation.
One month of higher core inflation does not establish a sustained reversal, but it indicates that the slowdown in headline inflation should be interpreted alongside other price measures.
Housing Costs May Continue to Outpace Household Relief
For renters, a reduction in headline inflation does not automatically translate into lower rents or smaller housing bills.
Rental prices reflect several factors, including the supply of available homes, location, demand, landlords’ operating expenses, maintenance costs and the cost of providing alternative accommodation. In markets where housing supply remains constrained, rents may continue to rise even as general inflation moderates.
NHM’s earlier analysis of Nigeria’s rent crisis examined how rental increases in Lagos and Abuja can diverge from official inflation trends. That distinction remains important: consumer inflation measures changes across a broad basket of goods and services, while individual households experience housing costs according to their location, tenancy arrangements and the timing of rent reviews.
For tenants facing annual or multi-year rent payments, the immediate financial burden may therefore remain high despite the latest reduction in headline inflation.
Prospective homebuyers face a related challenge. Lower inflation can improve financial planning if it persists, but elevated property prices, deposit requirements and mortgage repayments can still place homeownership beyond the reach of many households.
Construction Costs Remain a Challenge for Developers
The inflation trend also matters for property developers, who must manage the cost of land, building materials, labour, transport, power and project financing.
A slower rate of general price increases may improve cost planning, but it does not mean that construction inputs have returned to earlier price levels. Where materials, labour or energy remain expensive, developers may continue to face high project budgets and pressure on profit margins.
Higher costs can affect the pace of new housing delivery. Developers may delay projects, reduce the scale of construction or target higher-income buyers who can absorb elevated prices. Smaller developers may also struggle to finance projects when working capital and borrowing remain expensive.
These pressures have implications for housing affordability. If the cost of delivering homes remains high while household purchasing power remains constrained, the market may continue to favour buyers and tenants with stronger incomes, leaving lower- and middle-income households with fewer options.
The September inflation report does not establish that construction costs rose by the same rate as core inflation. Rather, it provides a broader economic signal that must be considered alongside actual prices for building materials, labour, energy and property financing.
Energy and Transport Costs Could Sustain Price Pressures
Energy and transport expenses are important links between the wider economy and the property market.
Developers rely on fuel-powered logistics, machinery and generators where reliable grid electricity is unavailable. Landlords and property managers also face electricity, water-pumping, maintenance and security expenses, while households must account for transport between their homes and places of work.
When these costs rise, businesses may pass some of the additional burden to customers, tenants or property buyers. Higher transport costs can also affect the attractiveness of residential locations, particularly where residents depend on daily commuting.
Recent inflation reporting has highlighted a sharp increase in monthly energy inflation, reinforcing concerns that higher energy costs could complicate the broader disinflation trend.
For the housing sector, sustained energy and transport costs can therefore weaken the benefits of lower food prices by limiting how much income households have available for rent, mortgage payments and other housing expenses.
What the Inflation Trend Means for Housing Finance
The direction of inflation is also relevant to mortgage lending and property investment.
A sustained decline in inflation could improve the environment for monetary easing, potentially creating room for lower borrowing costs over time. However, mortgage rates depend on more than headline inflation: lenders also consider funding costs, credit risk, loan duration and broader financial-market conditions.
The Central Bank of Nigeria reduced its Monetary Policy Rate to 23% in September 2026, but that does not mean mortgage rates will fall immediately or by the same amount. The cost and availability of long-term housing finance will depend on how banks and mortgage institutions respond to changing monetary and market conditions.
For developers, more affordable financing could support project expansion and housing delivery. For homebuyers, lower borrowing costs could reduce repayment burdens, provided lenders make suitable products available and property prices remain within reach.
However, if core inflation and energy costs remain volatile, financial institutions may continue to price in economic risks. This could slow the transmission of lower headline inflation into more accessible housing finance.
Outlook: Lower Inflation Must Translate into Lower Living Costs
Nigeria’s September inflation figures show progress in slowing the annual rate of price increases, but they do not establish that households have regained the purchasing power lost during previous periods of high inflation.
The decline in monthly food prices offers some relief, while the increase in monthly core inflation underlines the need to monitor price movements beyond seasonal food supply.
For the housing market, the key indicators will include rental-price trends, construction input costs, energy and transport expenses, and the availability and cost of mortgage finance. These measures will help show whether improving headline inflation is translating into better housing affordability.
A sustained improvement would require more than a lower inflation reading. Greater housing supply, predictable development costs, improved infrastructure and access to long-term finance will remain important to helping households secure suitable accommodation.
For now, the September figures point to a slowing rate of inflation rather than a broad reduction in the cost of living. Renters, developers and homebuyers will need to see more sustained improvement in the costs directly affecting their housing decisions before the benefits become tangible.
READ MORE