NHM Partners Bujeti to Launch Concrete & Cash Flow, a premium report on Nigeria’s real estate market
Bujeti Launches Concrete and Cashflow Report
A report built from ten operator interviews finds a market repriced into national significance, and a financial layer beneath it that almost nobody can see.
When Nigeria rebased its national accounts, real estate came third among all sectors, displacing crude oil and natural gas, with output of ₦41.3 trillion in 2024. It was the kind of number that usually settles an argument. Instead, it opened one.
A sector that size should be able to say how many homes the country is short. Nigerian real estate cannot, not within a factor of two. The National Housing Data Technical Committee, coordinated by the Nigeria Mortgage Refinance Company, put the deficit at 14.925 million units in January 2026, replacing years of unverified figures above 20 million. Four months later, Lagos State warned that counting 15.2 million structurally defective or substandard homes pushes the effective shortage close to 28 million.
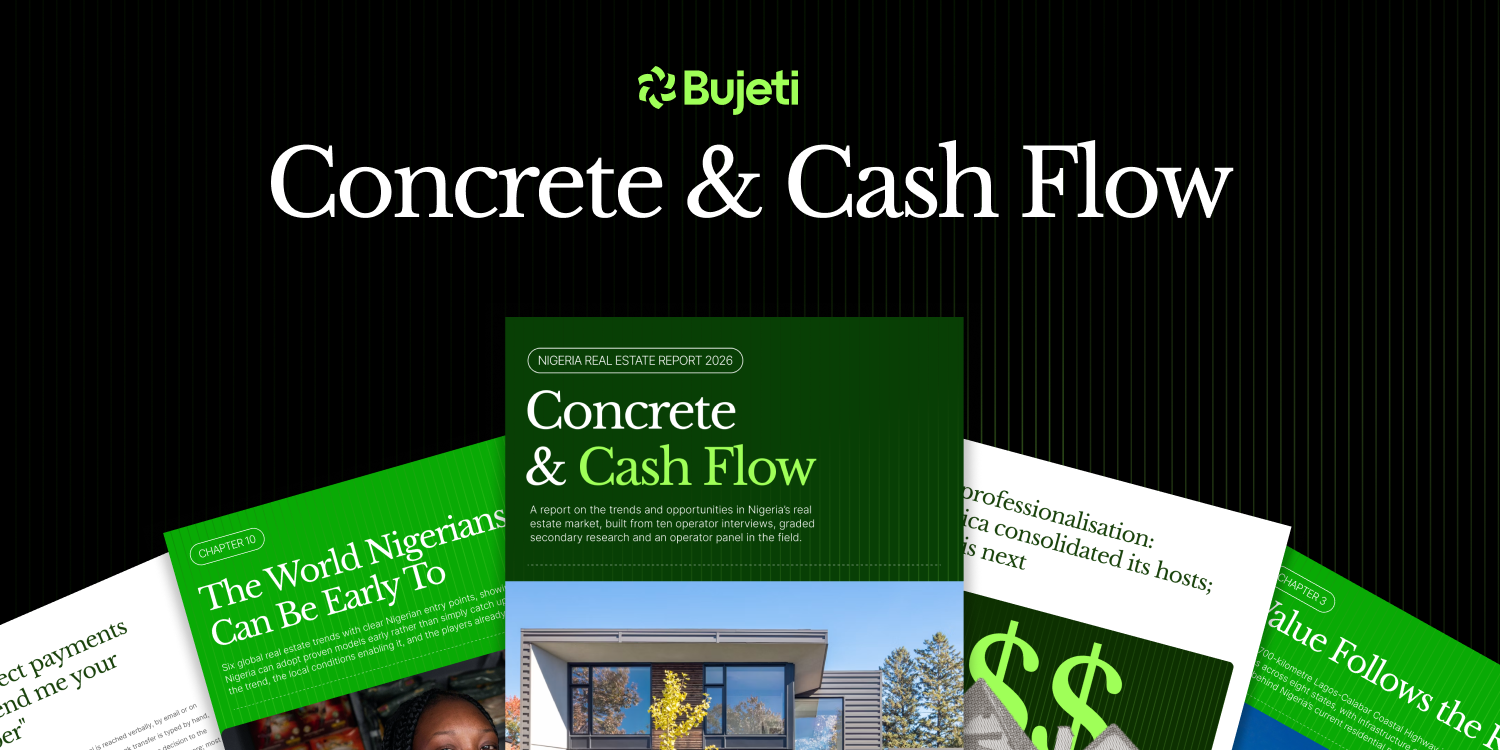
That gap between the size of the industry and the quality of what is known about it is the subject of Concrete & Cash Flow, published this week by Nigeria Housing Market with the finance platform Bujeti. It is built from interviews with ten named operators conducted on an identical question frame over two months, secondary research graded by confidence, and an operator panel still in the field.
Why Nigeria Housing Market put its name to it
For NHM, the report is an extension of the work the publication already does on the deficit, Lagos land prices and the policy decisions that move them. What it adds is the layer beneath the prices.
“This publication exists because Nigeria’s largest asset class has been covered as a rumour,” said Babatunde Akinpelu, founder and lead housing analyst at Nigeria Housing Market. “Renters, buyers, developers, financiers, policymakers and the diaspora all make consequential decisions from different sets of numbers, most of them unsourced and many of them supplied by whoever stands to gain from the transaction. The asymmetry costs ordinary people real money. A buyer abroad reads that a corridor has doubled and wires funds against a survey plan. A first-time investor budgets for the land and not for the title. Those are failures of available information, not failures of intelligence, and they are fixable.”
Concrete & Cash Flow goes to that layer and asks the people who live in it. That is why we put our name on the cover rather than simply covering the launch.”
Ten operators, and where they refuse to agree
The contributors are not anonymous sources, and they contradict each other in print.
On land banking, the report sets out three positions and declines to pick one. Yemisi Itepu, who spent years running operations at one of the country’s largest land-sales groups, makes the case for buying ahead of industrialisation, and the cycle supports her: land along the Ibeju-Lekki and Epe axis rose about 35 percent year on year, with plots that sold for ₦15 million in 2024 now asking ₦25 million and above. Nnamdi Uba, whose platform Sytemap sits across the transaction layer, answers in five words: land banking is for beginners. A plot pays no rent and services no expense, while a building earns from month one and appreciates anyway. Ekeh Emmanuel, building in Enugu, describes diaspora buyers who keep purchasing land in a region many consider too insecure to live in, a refuge asset rather than an investment, and one not dislodged by yield arithmetic.
“Where they converge, you have a signal strong enough to act on,” said Caleb Nnamani, the report’s author. “Where they diverge, you learn something more useful: that this is not one market. Three operators gave three answers on land banking and all three were right about a different buyer. Editing that down to a single verdict would have made the report tidier and less true.”
What illegibility costs
The consequence shows up in the price of capital. Commercial mortgages in the report price between 25 and 32 percent. The subsidised federal rail, MREIF, lends at 9.75 percent fixed for up to 20 years and has now disbursed more than ₦140 billion to over 2,000 borrowers across 27 states, a rail that barely existed three years ago and still reaches a fraction of the market.
Tunde Balogun, whose company SmallSmall pioneered monthly rentals, puts the asymmetry plainly in the report: the people actually cashing out in Nigerian real estate are the finance guys. Banks post record profits while the developers borrowing from them declare losses. The report’s reading is that opacity is priced into every loan, and nobody has offered the market a rebate for legibility.
Construction made it urgent
Input costs have turned a measurement problem into a survival one. A 50kg bag of cement that sold for about ₦7,500 in late 2025 rose to between ₦9,000 and ₦10,000 by early 2026 and now retails between ₦12,000 and ₦15,000 depending on brand and location, with the competition regulator opening an industry-wide investigation in August. Materials represent 50 to 70 percent of what a project needs.
The state, meanwhile, has repriced the cost of being legal. Lagos activated its 2026 Fair Market Value framework on 1 May. No fee rate changed; the official valuations those rates are calculated against rose sharply, taking Governor’s Consent on a Lekki Phase 1 transaction from ₦12 to 18 million to between ₦40 and 90 million. Set beside the report’s estimate that no more than one in five Nigerian buildings carries full documentation, the sequence is complete: a state that has just repriced legality is repricing a service most of the market had already stopped buying.
What the numbers let people do
The report is organised so that each finding ends in an action rather than an observation. A developer can budget title and perfection at acquisition instead of discovering the Blue Book at closing. An investor can test a corridor claim against a named catalyst, a verified title and a realistic holding period. A lender gets, in one document, the reason Nigerian project lending prices where it does, and the operators who can answer it. A policymaker can read the deficit against what is actually being built, which is largely not the ₦25 million to ₦200 million band where most purchases occur. A diaspora buyer gets the questions to ask before wiring funds against a survey plan.
“A number is only useful if somebody can act on it,” Nnamani said. “That is why every chapter ends in an opportunity rather than a warning.”
Why a finance platform co-published a property report
Bujeti has been direct about its reasons, and they have two halves. The first is that Nigerian real estate attracts more interest than almost any sector in the economy and holds less verified knowledge of its own operations, a gap no amount of capital closes on its own. The second is commercial and openly stated: property moves volume, with a single development paying dozens of vendors a month across several accounts, which makes it the strongest case in the economy for payment efficiency and the weakest current practice.
"We are not trying to be right about Nigerian real estate. We are trying to give the people who run it a shared set of facts to disagree over. Right now a developer in Epe, a diaspora buyer in Houston, an estate manager in Ikeja and a policymaker in Alausa are all making consequential decisions from different numbers, most of them unsourced, many of them supplied by whoever stands to gain from the transaction. You cannot build policy on that, and you certainly cannot price risk on it. A shared record is the cheapest piece of infrastructure this industry could give itself, and it has been missing for thirty years," said Caleb Nnamani, the report's author and Bujeti's PR and storytelling lead.
Concrete & Cash Flow is the first edition of a planned annual measurement. It is free to read at bujeti.com/reports/real-estate.